
Underpaid Insurance Claim? How to Prove the Gap and Get the Rest Paid
A partial payment that does not cover the repair is an underpayment, not a denial, and it is rarely the last word. Here is how to find what the carrier left out and get the rest of the claim paid.
The Insurance Appraisal Clause: Your Option When the Offer Is Too Low
After a lowball offer most policyholders think the options are accept it, argue, or hire a lawyer. There is a fourth already written into the policy, and it produces a binding number without going to court.
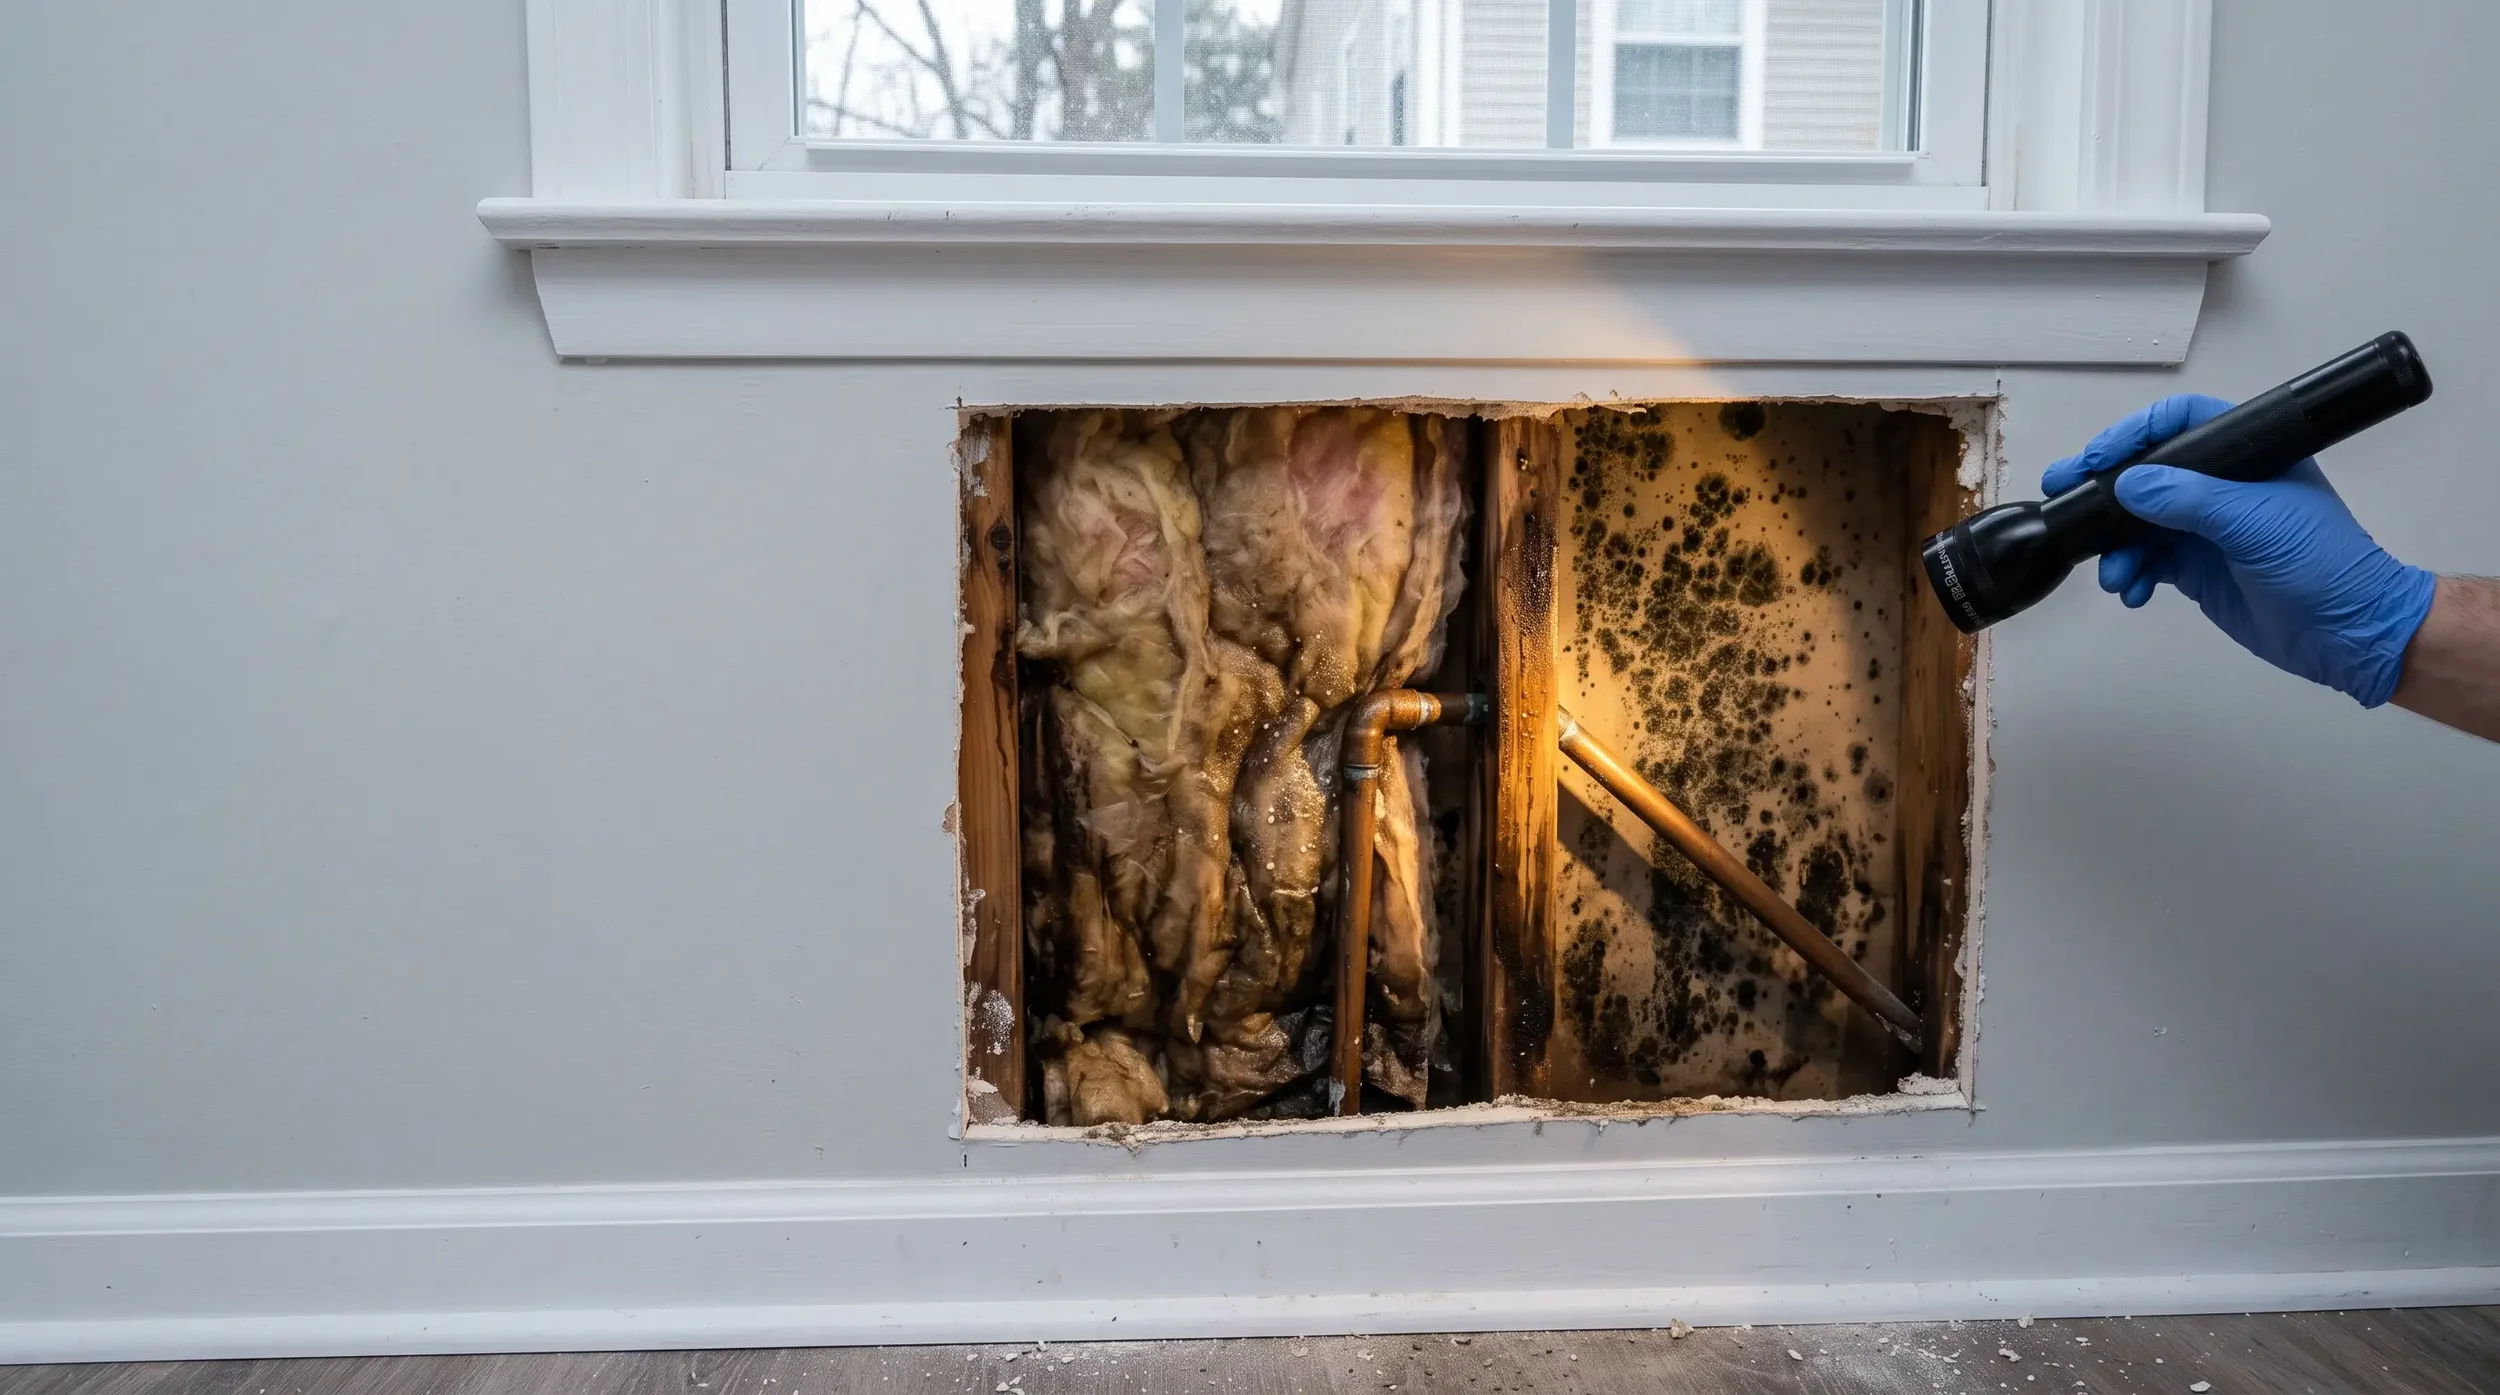
Is the HOA Responsible for Water Damage? It Depends on What Got Wet and Why
When water comes through a condo ceiling, the association's policy and your own usually both cover part of the loss. Which part is yours depends on what got wet and why it got wet, and Florida, Minnesota and Wisconsin answer that differently.
Loss of Use Coverage: It Pays the Increase, Not the Total
Loss of use is the coverage most often underclaimed, and the reason is one misunderstanding: it pays the increase in your living costs, not the total. If your mortgage continues and you also pay rent, the claim is the rent.
HOA Master Insurance Policy: What It Covers and What It Excludes
Where the master policy stops and your policy starts is written into Florida statute, not left to the fine print. Here is exactly what the master policy must cover, the items it must exclude, how to get a copy in 10 working days, and how to size your HO-6 against it.
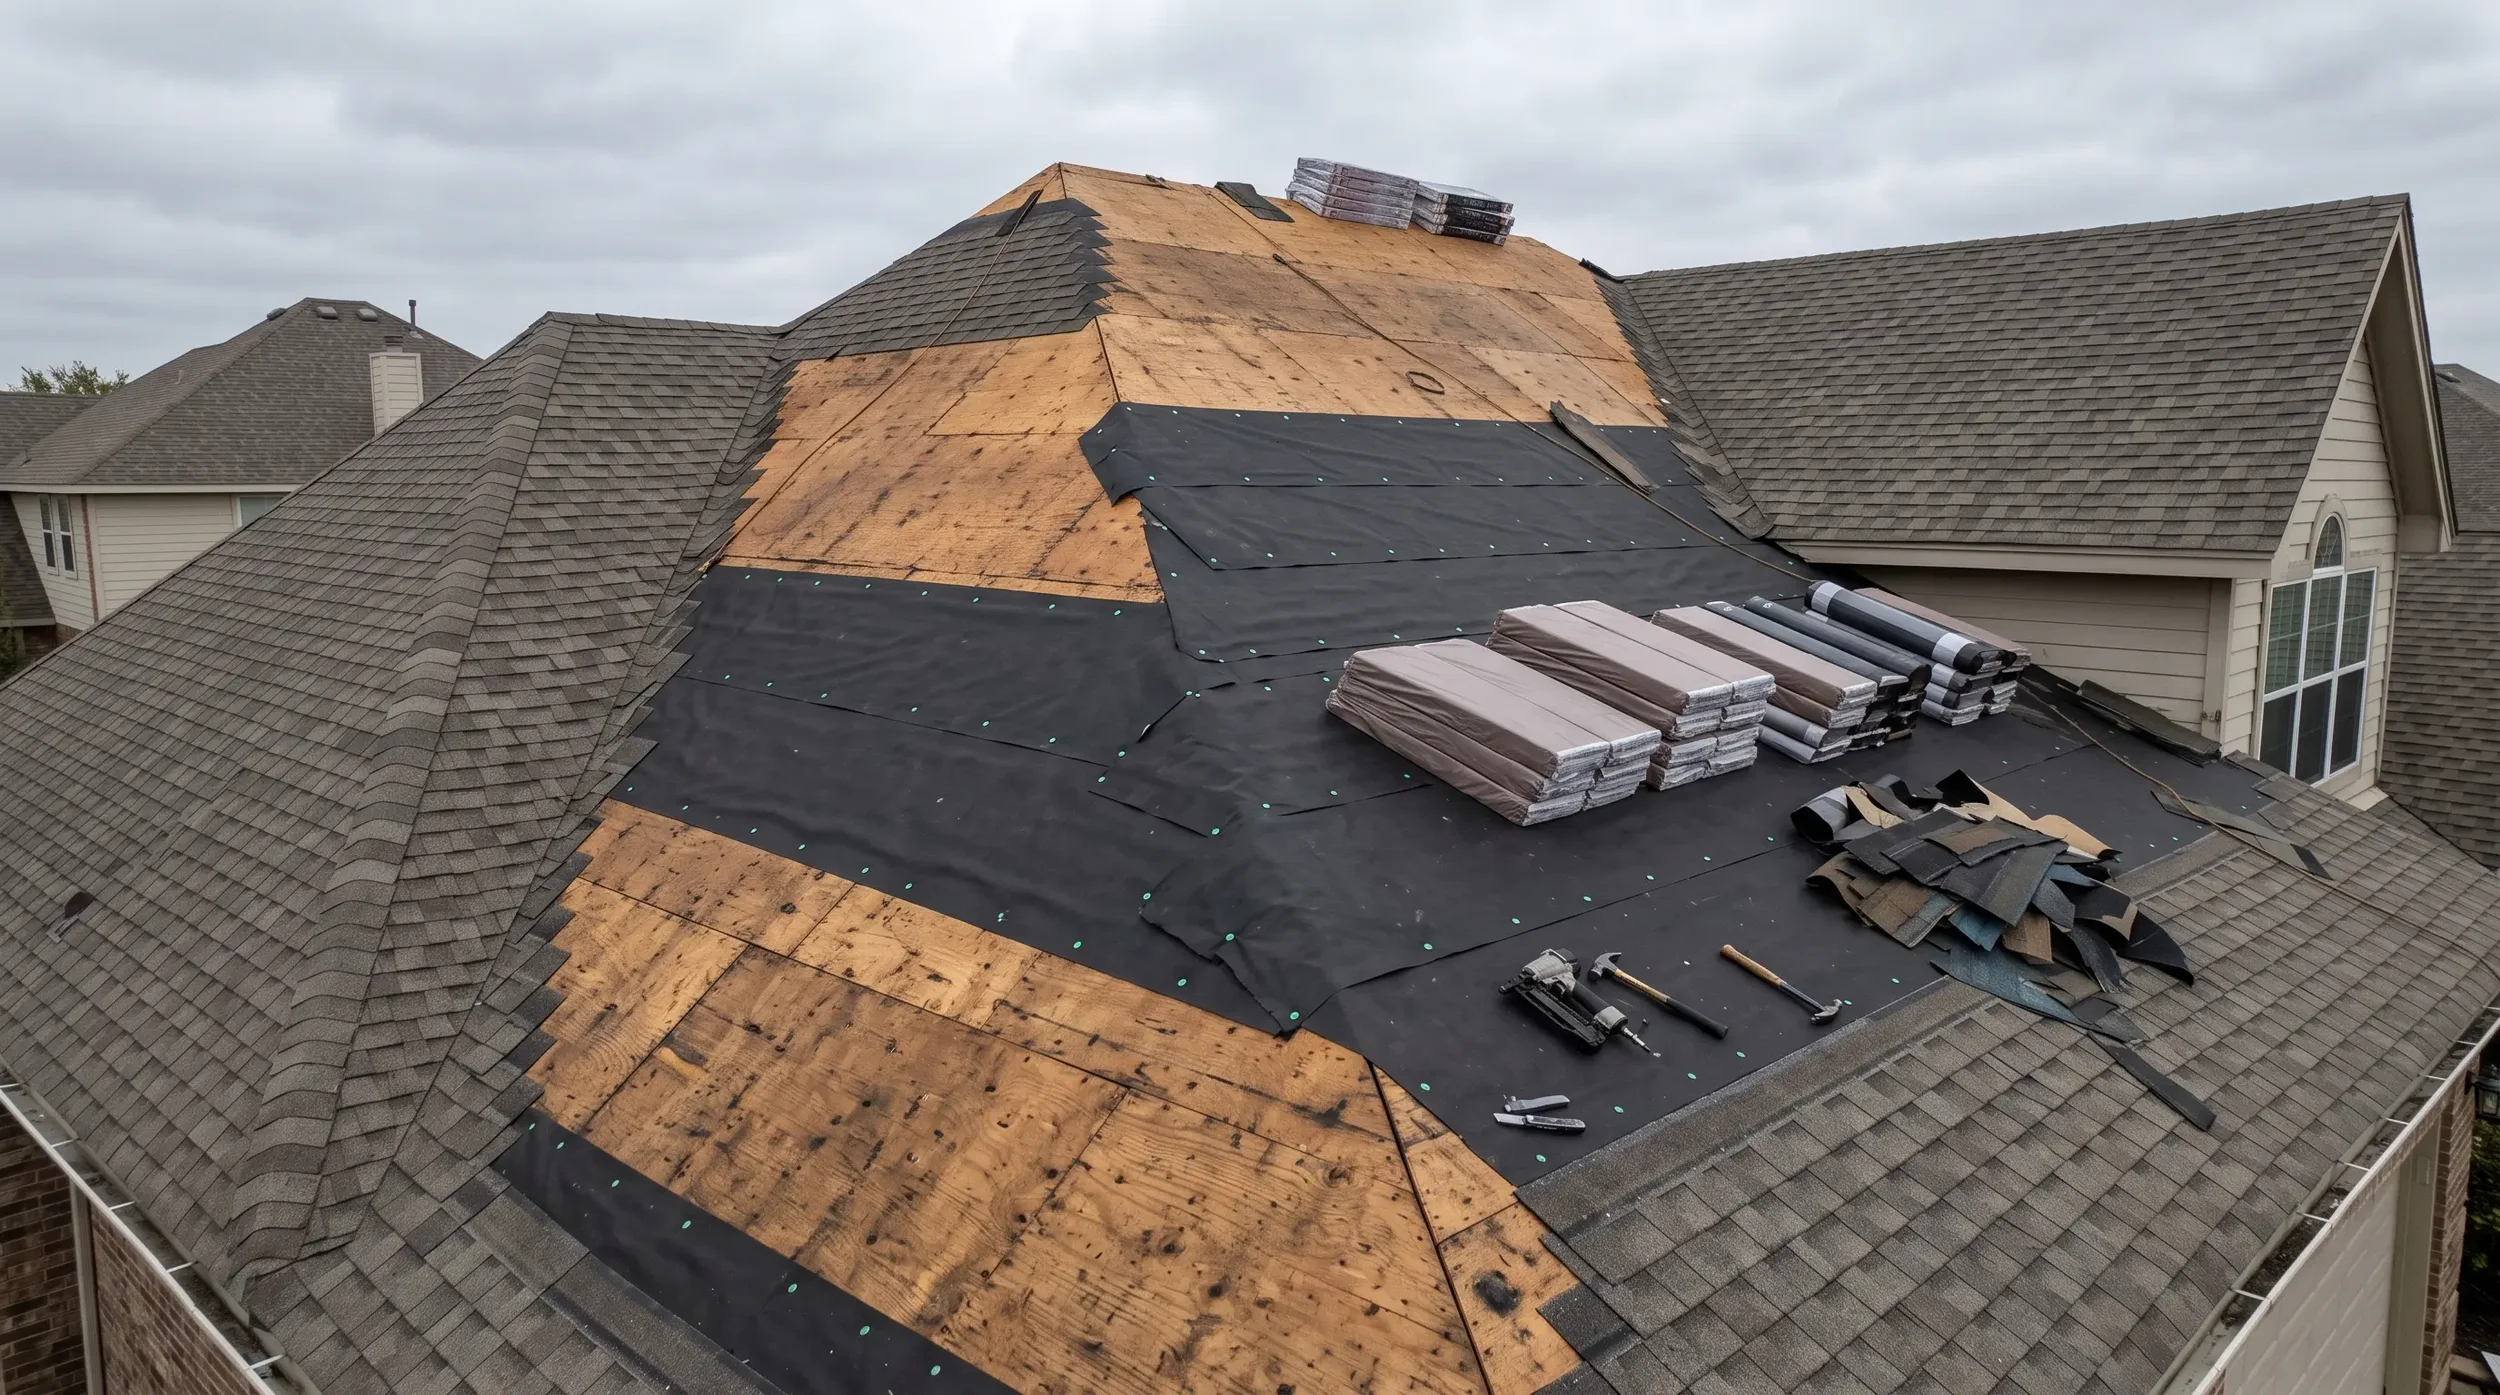
Ordinance or Law Coverage: The Part of Your Claim Nobody Scopes
Standard property insurance pays to put your building back the way it was. It does not pay to bring it up to a code written after it was built, and that gap is the most common uncovered cost in a large claim.

Commercial Property Damage Claims: The Roof and Hail Coverage Owners Miss
A commercial property damage claim is not a bigger version of a residential one. Three provisions in your declarations - coinsurance, roof endorsements and ordinance or law - decide most commercial roof and hail settlements before an adjuster ever climbs a ladder.

Filing a Business Interruption Insurance Claim: What Most Owners Miss
Business interruption is not one line on a policy - it is a cluster of coverages, and carriers pay the ones you ask for. Here are the three owners leave on the table, and the clock your insurer is on in Florida, Minnesota and Wisconsin.
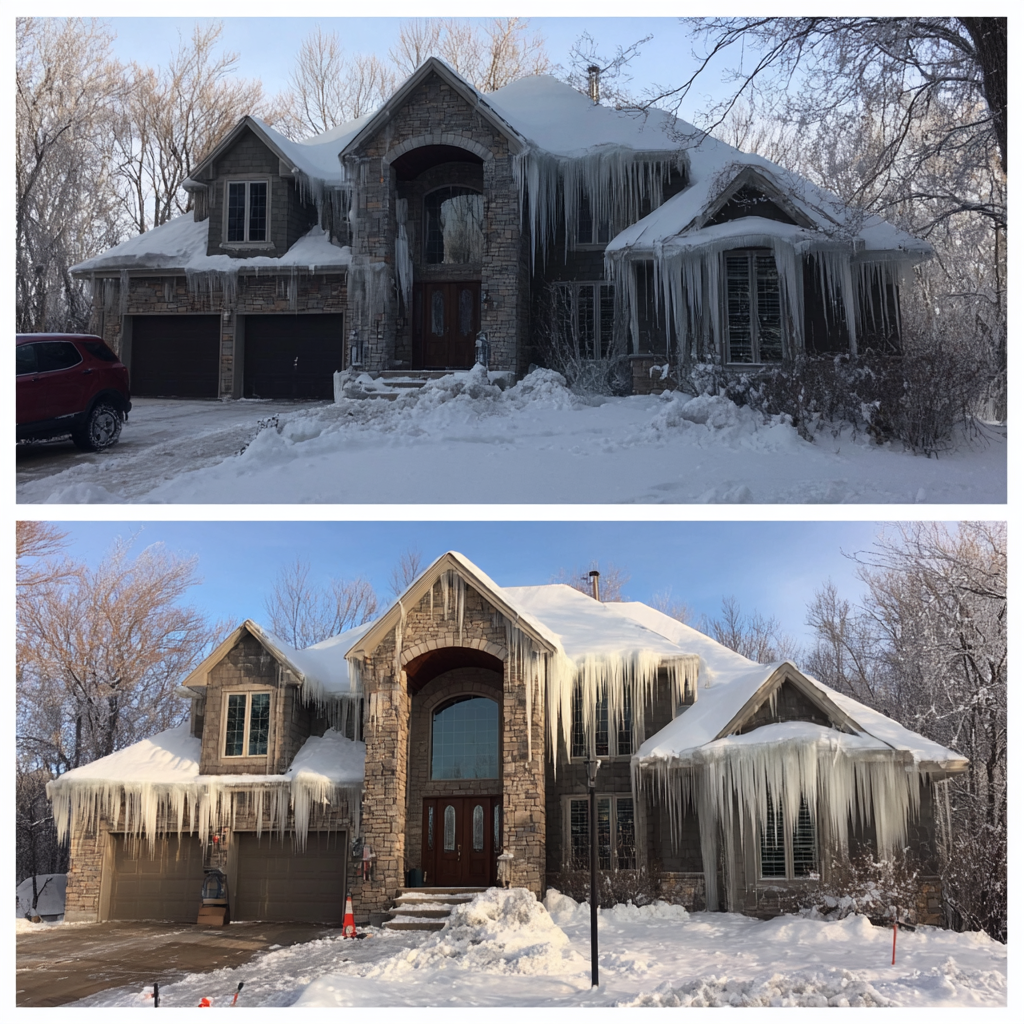
Does Homeowners Insurance Cover Ice Dams? A Minnesota Claims Guide
Minnesota policies cover the water an ice dam lets in, not the ice that let it in. Here is where that line actually falls, the building-code argument that undercuts a neglect denial, and the ten-business-day clock your insurer is on.
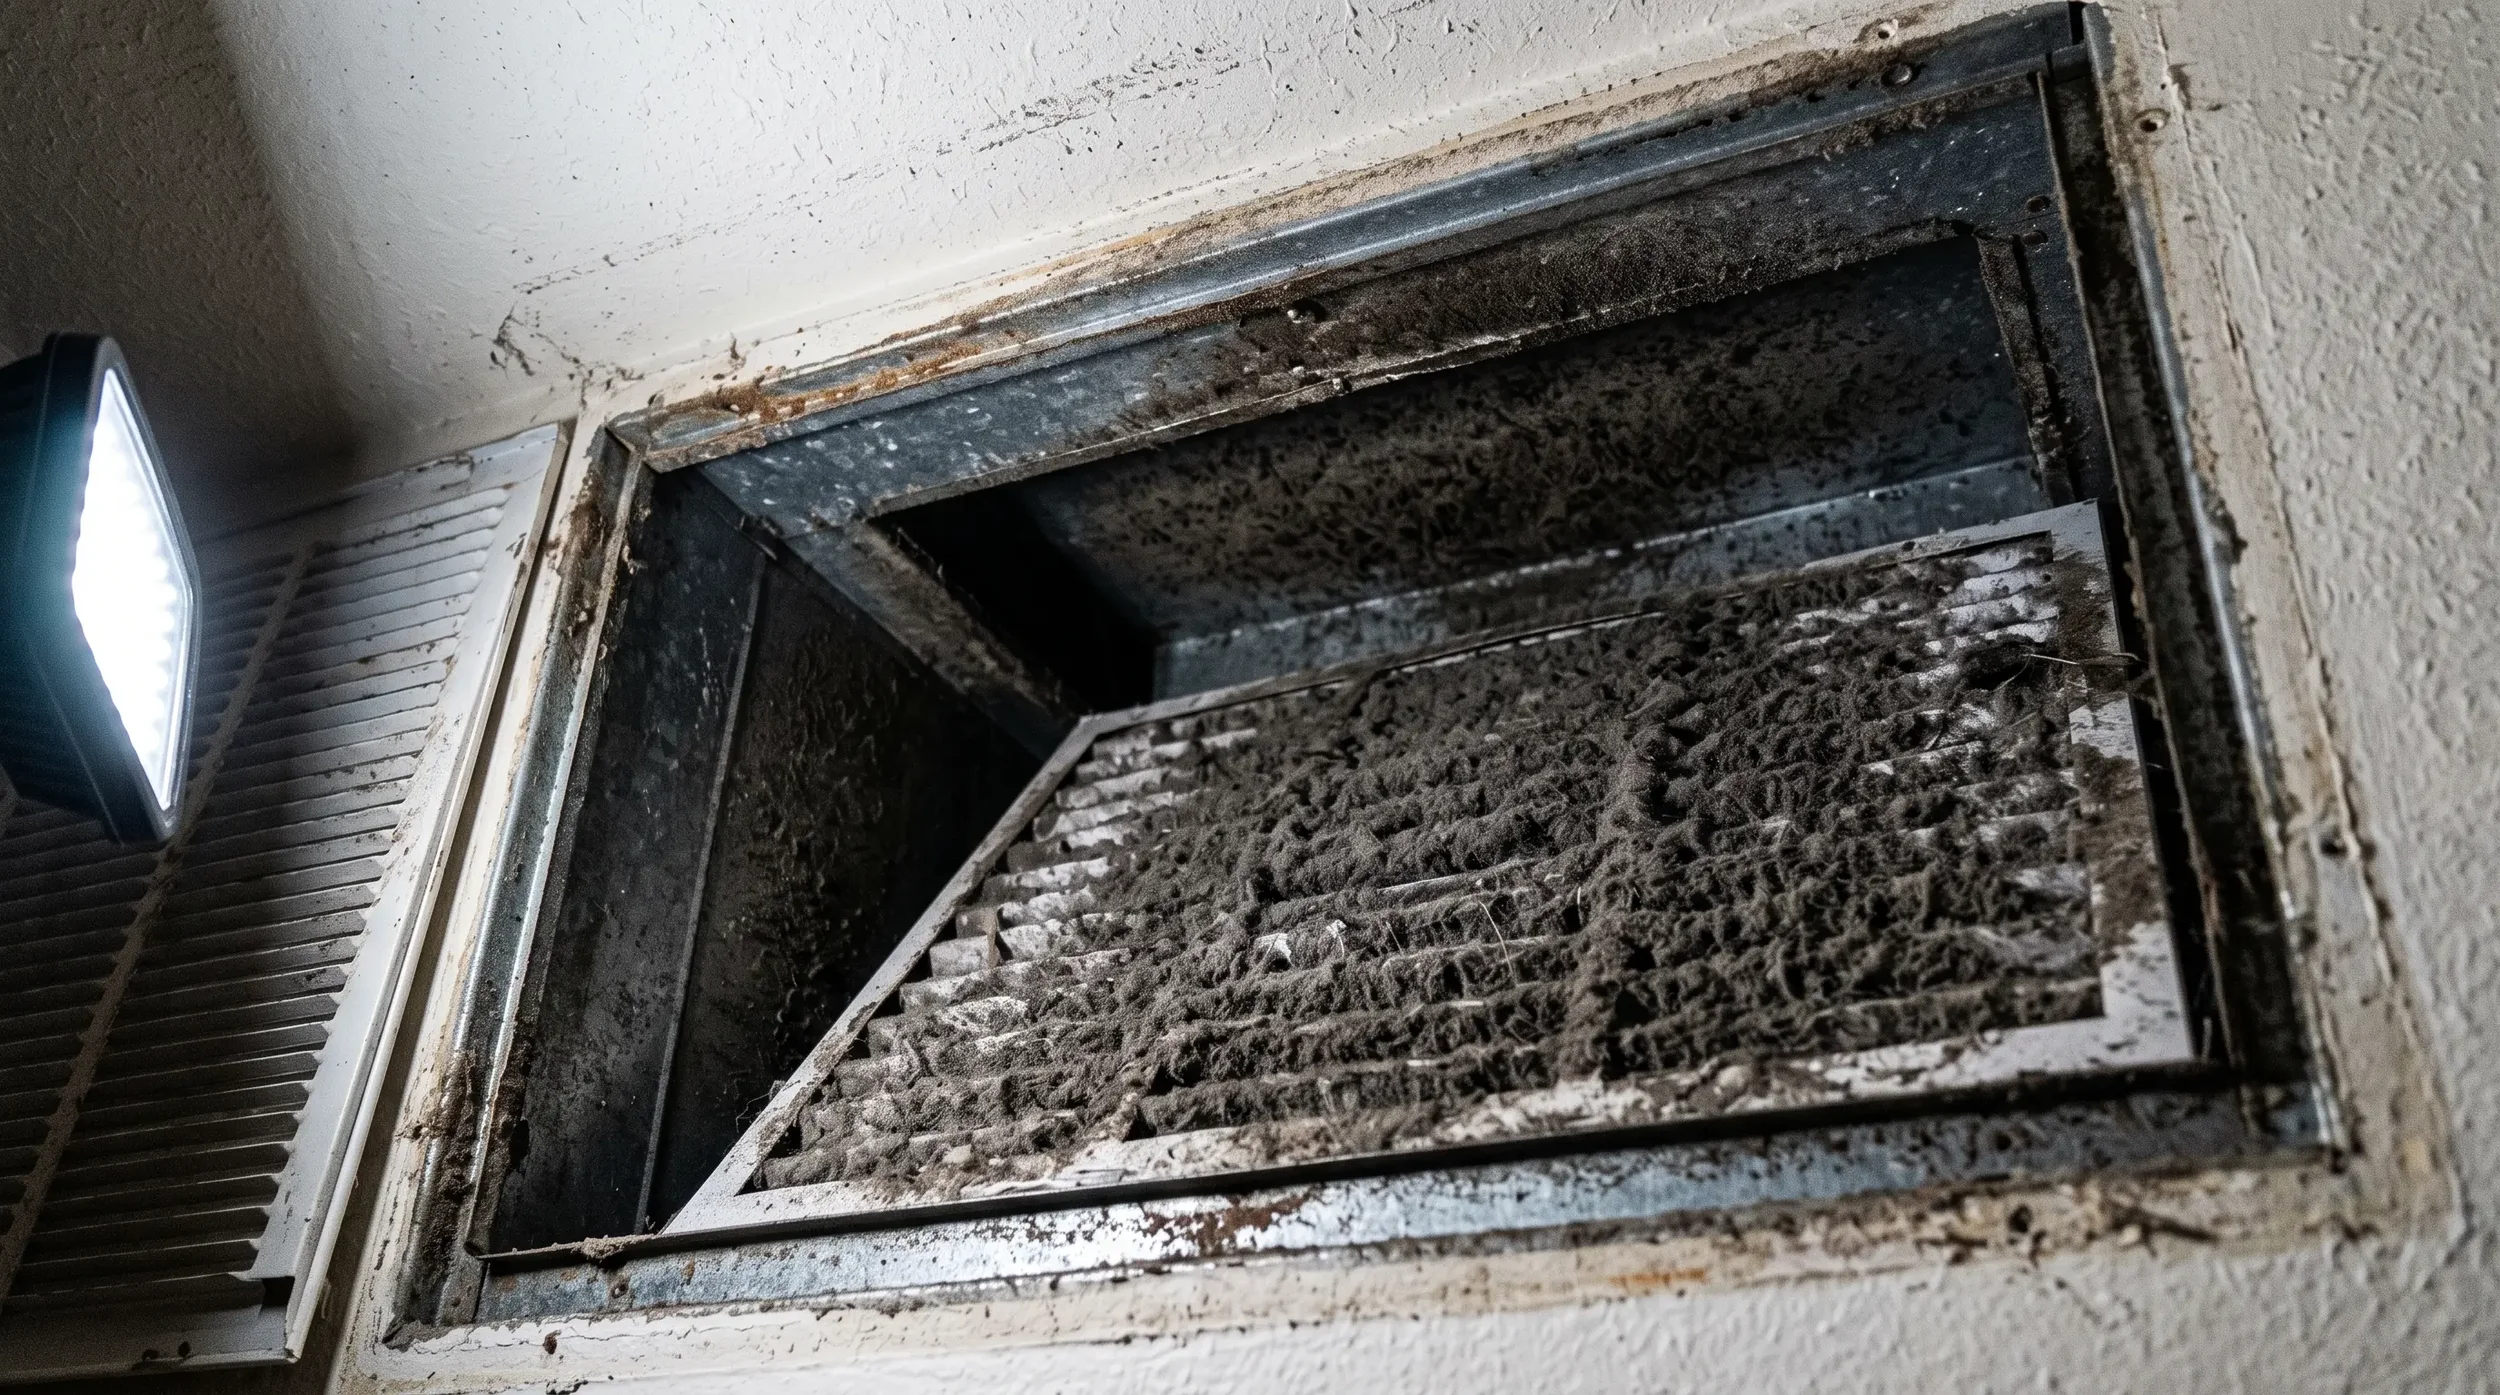
Smoke Damage Insurance Claim: What Carriers Underpay
Smoke damage is not a footnote on the fire claim. It migrates through the whole building, it crosses property lines from a neighbor's fire, and it lands in the gray area between cleaning and replacement where most of the money is.
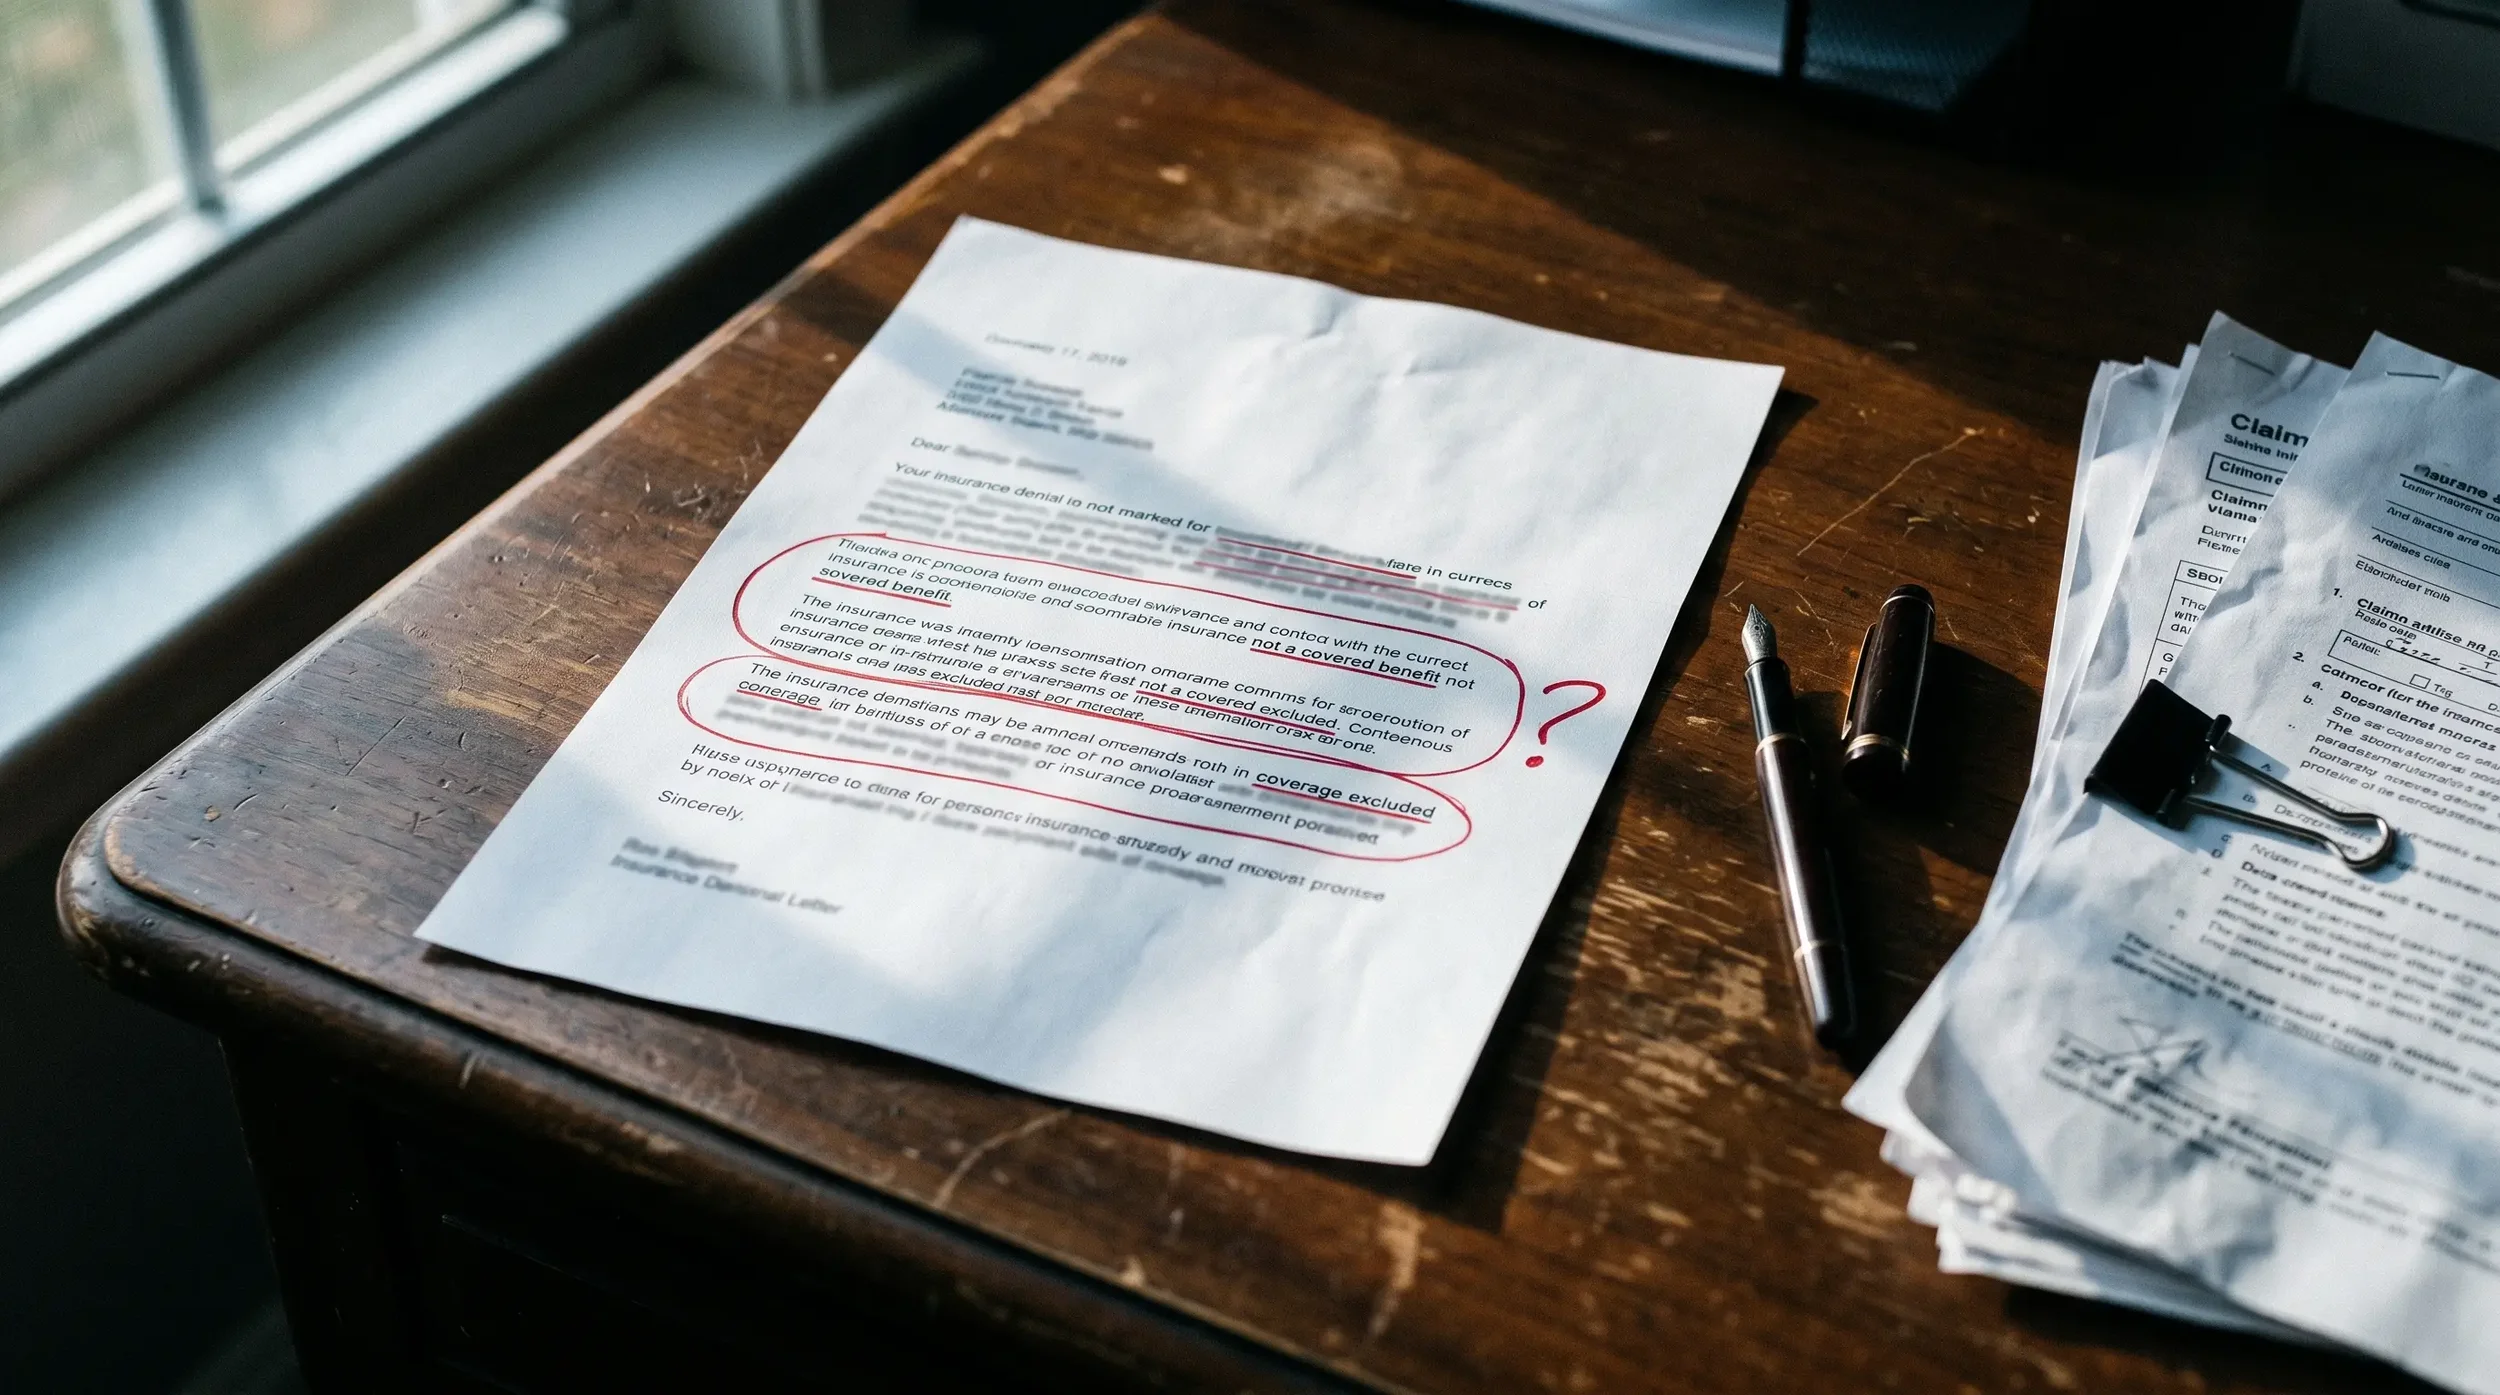
Why Do Insurance Companies Deny Claims? (7 Tactics, Decoded)
Most claim denials use the same 7 tactics — pre-existing damage, wear-and-tear, anti-concurrent causation, and others. Here's how each one works, the policy language insurers cite, and how to fight them.
Are Public Adjusters Worth It? An Honest Answer
Public adjusters earn their fee on complex, denied, or underpaid claims. They don't make sense on every claim. Here's the honest breakdown of when to hire one — and when not to.
How Much Does a Public Adjuster Cost? (FL, MN & WI Fee Breakdown)
Public adjusters work on contingency — no upfront fees. Here's exactly what we can charge in Florida (capped by statute), Minnesota (negotiable), and Wisconsin (capped during catastrophes).
What Is a Public Adjuster? (And When You Actually Need One)
A licensed public adjuster works for you — not your insurance company. Here's exactly what we do, when we earn our fee, and how to verify a PA before signing anything.

Hail Damage Claims in Bloomington, MN: What Your Insurer Won't Tell You About Your New Deductible
Bloomington homeowners are paying more out of pocket on hail claims than ever — and most don't realize it until the check arrives. Here's what your insurer isn't telling you about percentage deductibles, missed line items, and how to get the settlement you're owed.
When Should You Hire a Public Adjuster?
Most policyholders assume their insurance company will take care of them — especially after years of loyalty and on-time premiums. That assumption costs more claims than any single insurer tactic. Here's an honest breakdown of when a public adjuster changes your outcome, when you're fine without one, and the one timing mistake that locks you out of help entirely.
Anti-Concurrent Causation: How Florida Insurers Use This Clause to Deny Panhandle Storm Claims
Anti-concurrent causation is costing Florida homeowners millions. Learn how insurers use it to deny claims and how to fight back.
Insurance Claims for Military Families and Homeowners Near Eglin AFB and Hurlburt Field
Military homeowners near Eglin AFB and Hurlburt Field face unique insurance claim challenges. Learn about SCRA protections, PCS moves, and off-base housing rights.

Tallahassee Public Adjuster: A Licensed Insider's Guide to Inland Storm Claims
Tallahassee storm and tornado damage claims require special handling. Learn the unique issues Leon County homeowners face and how to maximize your recovery.
Condo and HOA Insurance Claims in Destin: A Guide for Emerald Coast Property Owners
Destin condo and HOA insurance claims are complex. Learn about master policies, HO-6 coordination, deductibles, and how public adjusters help you recover.