Coinsurance Penalty: Why Your Claim Payment Was Cut, and How to Push Back
TL;DR — Coinsurance Penalty on a Property Insurance Claim
- A coinsurance penalty is not a coverage denial. The loss is covered. The carrier is reducing what it pays because it says you did not carry enough insurance on the building.
- The formula is fixed, but the inputs are not. Insurance carried divided by insurance required, times the loss. The "required" figure comes from a valuation the carrier performs after your loss — and a valuation is an opinion, not a fact.
- Two different penalties share the name. Commercial property forms reduce the payment proportionally. Homeowners forms usually drop you from replacement cost to actual cash value instead. Different math, different fix.
- On a total loss, a valued policy law can change the math. Florida, Minnesota, Wisconsin, North Dakota and South Dakota each have a statute making the policy amount the measure of a total loss — each with real limits, and Florida's and Minnesota's both leave room for a coinsurance clause that meets the statute's conditions.
- Condo and homeowners associations get hit hardest, because blanket limits across several buildings drift furthest from current replacement cost. Florida law requires a condominium association's replacement cost to be re-determined at least every three years.
- If the fight is about the number, there is a process for that. Most property policies contain an appraisal clause, and a valuation dispute is exactly what it was written for.
The Line Item Nobody Explains Until It Costs You
A coinsurance penalty almost always arrives the same way. Coverage was never in question, the adjuster agreed the damage happened, the estimate looks roughly right — and then the payment is thousands less than the estimate, with a line on the worksheet nobody walked you through.
Search the term and you will find a dozen insurance agencies explaining how to avoid a coinsurance penalty by insuring your building correctly. That advice is sound and it is also useless to you now, because the loss has already happened and the penalty has already been applied.
This article is about the other half of the problem: what the penalty actually is, which number it depends on, and what you can still do once it shows up on your settlement.
Free 15-minute claim review
If a coinsurance penalty has been applied to your claim, we will read the worksheet with you and tell you whether the valuation behind it holds up. No upfront fee. Our fee comes out of the recovery and is agreed in writing before we start.
What a Coinsurance Penalty Actually Is
A coinsurance condition is a clause in a property policy requiring you to carry insurance equal to a stated percentage of the property's value. Eighty percent is the most common; ninety and one hundred percent both appear. The percentage sits on your declarations page, usually beside the building limit.
If you meet it, nothing happens. If you do not, the insurer pays only the proportion of your loss that your actual limit bears to the limit you should have carried:
(Insurance carried ÷ Insurance required) × Loss = Amount recoverable, less your deductible.
Here is the arithmetic on a hypothetical building, with round numbers chosen for clarity rather than drawn from any real claim. Say the policy carries an 80% coinsurance condition, the insurer values the building at $2,000,000 at the time of loss, and the building limit is $1,200,000. The required limit was $1,600,000, so you carried three quarters of what the clause demanded. On a $400,000 loss, the insurer pays $300,000 before the deductible comes off, and the remaining $100,000 is yours.
Notice what that penalty is proportional to. It is not proportional to how badly you were underinsured in dollars. It is proportional to the ratio, and the ratio is set by a number the carrier produced after your building was damaged.
Two Different Penalties Wear the Same Name
This is where most of the published explanations go wrong, and where the confusion costs policyholders real money.
Commercial property forms carry an express coinsurance condition, and it works exactly as described above: proportional reduction of the payment. Commercial coinsurance is a routine part of how commercial property is rated, and higher percentages usually come with a premium discount in exchange.
Most homeowners forms do something different. Rather than reducing the payment proportionally, they make replacement cost settlement conditional on insuring the dwelling to at least eighty percent of its full replacement cost. Fail that test and you do not get a proportional haircut — you get moved to actual cash value, which means depreciation comes off the whole claim.
Those are two unrelated penalties with the same nickname. One is a fraction of your loss; the other is the age of your roof, your siding and your windows subtracted from the cost to replace them. The fix is different in each case, which is why the first thing to establish is which one you are actually facing.
⚠️ One honest caveat on this section. The eighty-percent replacement cost condition and the commercial coinsurance condition are policy form language, not statute. No state law imposes either one, although Florida, Minnesota and Wisconsin each have a statute on when a coinsurance clause is allowed, covered further down.
They vary between carriers and between editions of the same form. So the only authority on which one applies to you is your own policy — and the relevant words are in the loss settlement or coinsurance condition, not in the declarations.
If depreciation is the mechanism in your case, the holdback is often recoverable and the rules for getting it back are specific. We cover that in detail in recoverable depreciation, and the eighty-percent condition itself comes up constantly on older roofs — see will insurance cover a 20-year-old roof.
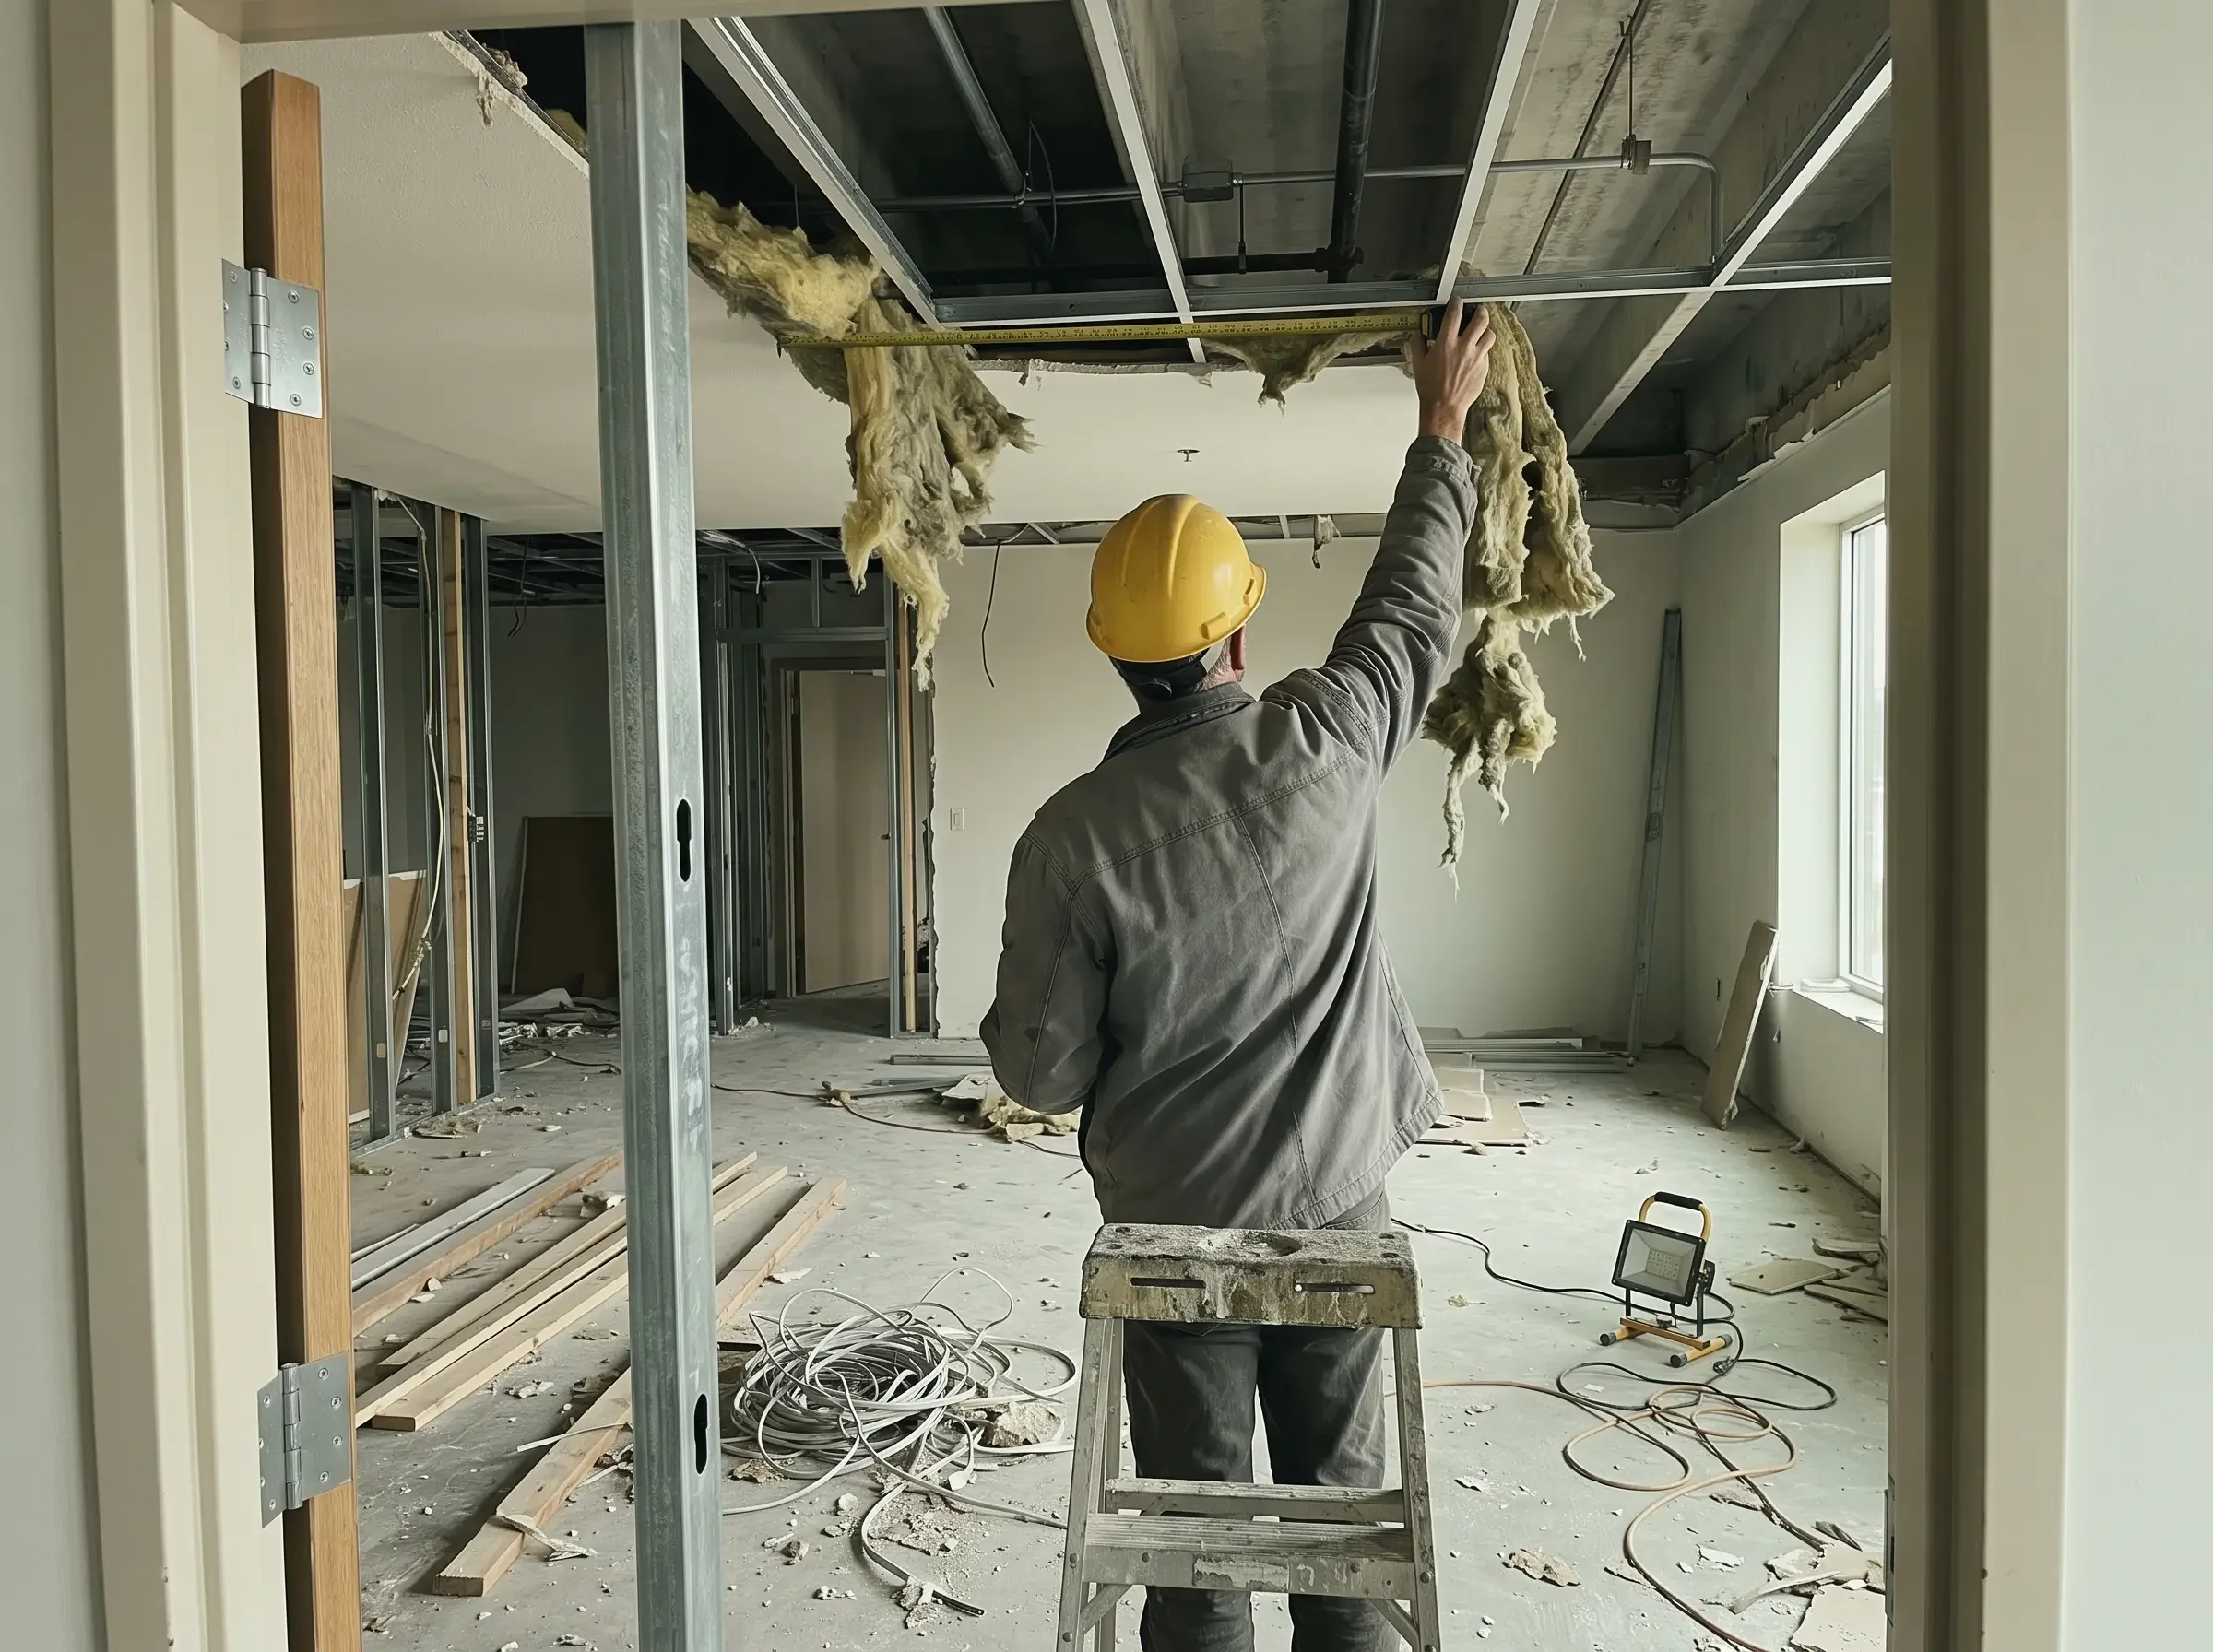
The Whole Penalty Rests on One Number, and the Carrier Picks It After the Loss
The coinsurance formula has three inputs. Your limit is printed on the policy, and your loss is being estimated by both sides already.
The third input is the value the required limit is calculated from. It is the only one that is genuinely contested, and it is the one almost nobody questions.
That value is the property's insurable value at the time of loss, not the figure anyone used at underwriting. Carriers say so plainly: the valuation that drives a coinsurance penalty is performed after the claim, by the insurer, on its own method. The replacement cost estimate your agent ran when the policy was written does not bind the company.
So a coinsurance penalty is, in practice, an opinion of value being used to reduce a payment. That reframes the entire problem.
You are not arguing about coverage, and you are not arguing about whether the damage is real. You are arguing about a construction cost estimate — which is work a public adjuster does every day.
Four places these valuations run high, in our experience:
- The wrong cost basis. A replacement cost estimator fed generic occupancy, construction class or finish-quality inputs produces a higher rebuild number than the building justifies. Ask which inputs were used.
- Non-insurable property counted as value. Many forms exclude foundations below the lowest floor, excavation, underground pipes and land values from the insurable amount. If those are inside the carrier's valuation, the required limit is inflated and the penalty with it.
- A valuation date that is not the loss date. Material costs move. A value pulled months after the loss, in a post-catastrophe market, is not the value at the time of loss.
- No worksheet at all. Sometimes the penalty is asserted with a number and no supporting calculation. Ask for it in writing.
If the carrier will not move on the number, most property policies contain an appraisal clause, and a dispute about the amount of loss is precisely what that clause exists to resolve. We walk through how that works, and when it is worth invoking, in the insurance appraisal clause.
On a Total Loss, a Valued Policy Law Can Change the Math
Here is the part the agency blogs leave out entirely, and it is the single most valuable thing on this page.
Every state we are licensed in has a valued policy law — a statute making the amount of insurance written in the policy the measure of the loss when the building is totally destroyed. Where one applies, the policy amount is the starting point for a total loss, not a value the carrier worked out afterward.
What these statutes do not all do is remove a coinsurance clause. Florida's and Minnesota's address coinsurance in so many words, and the other three valued policy sections do not mention it, so read your state's entry closely. All five were pulled from the live statute text on October 12, 2026.
Florida — Fla. Stat. § 627.702(1)(a). On the total loss of any building or structure in Florida caused by a covered peril, absent fraud or a change increasing the risk without consent, the insurer's liability "shall be in the amount of money for which such property was so insured as specified in the policy and for which a premium has been charged and paid."
Florida's version has a real limit built into it. Under § 627.702(1)(b), where a loss "was caused in part by a covered peril and in part by a noncovered peril," subsection (1)(a) does not apply and liability is limited to the portion caused by the covered peril — unless "the covered perils alone would have caused the total loss." That is the wind-versus-flood fight in statutory form. Separately, § 627.702(2) deals with a partial loss "by fire or lightning," where the insurer owes "the actual amount of such loss" up to the amount of insurance.
Two more subsections decide most coinsurance questions in Florida. Under § 627.702(4), the amount of a loss under subsections (1) and (2) "shall be subject to any coinsurance clause contained in the policy pursuant to s. 627.701." So Florida's valued policy law does not cancel a coinsurance clause: one that meets § 627.701 still applies, on a total loss as well as a partial one.
What Florida gives you instead is a checklist. Under § 627.701(1), a property policy may make the insured a coinsurer "only if" three things are true.
The policy, or a form attached to it, carries the words "Coinsurance contract: The rate charged in this policy is based upon the use of the coinsurance clause attached to this policy, with the consent of the insured." The coinsurance clause is "clearly identifiable." And the rate with and without the clause is furnished to the insured on request.
Look for that wording on your policy before you argue about anything else.
And under § 627.702(3)(b), subsections (1) and (2) do not apply when "two or more buildings, structures, mobile homes, or manufactured buildings are insured under a blanket form for a single amount of insurance."
North Dakota — N.D.C.C. § 26.1-39-05(1). The broadest of the five. Whenever a policy insures real property in North Dakota "against loss caused by or resulting from any covered cause of loss and the insured property is wholly or completely destroyed by any covered cause of loss without fraud," then "the amount of the insurance written in the policy is the true value of the property insured and the true amount of loss and measure of damages."
"Any covered cause of loss" means this is not limited to fire. The conditions attached to it are anti-fraud timing rules.
If the loss happens within sixty days of the policy's effective date, or within sixty days of the insured requesting a limit increase of twenty-five percent or more, the payment is the lesser of the policy value or what a partial loss would have paid. Renewals with smaller increases, increases due to the construction of additions, and increases the insurer approved before the loss are all carved out of that.
Builder's risk policies settle on the actual value of the completed portion. The section does not mention coinsurance.
Wisconsin — Wis. Stat. § 632.05(2). "Whenever any policy insures real property that is owned and occupied by the insured primarily as a dwelling and the property is wholly destroyed, without criminal fault on the part of the insured or the insured's assigns, the amount of the loss shall be taken conclusively to be the policy limits of the policy insuring the property."
The scope limits here come from case law rather than the statutory text, and they matter.
The building must be occupied by the insured primarily as a dwelling. In Cambier v. Integrity Mutual Insurance Co., 2007 WI App 200, a building rented to others for the fourteen months before a fire fell outside the statute.
It need not be exclusively residential — Seider v. O'Connell, 2000 WI 76. And it does not entitle you to the limits of every policy covering the building; Wegner v. West Bend Mutual Insurance Co., 2007 WI App 18, applied the pro rata statute, § 631.43(1), instead.
Wisconsin also permits coinsurance clauses by statute. Under § 631.45(2), a property policy "may limit the part of the loss to be borne by the insurer to a percentage of the total loss that corresponds to the ratio of the insured sum to a specified percentage of the value of the insured property." Neither section says how the two fit together when an owner-occupied dwelling is wholly destroyed.
Minnesota — Minn. Stat. § 65A.08 subd. 2(a). Absent a change increasing the risk without the insurer's consent, and absent intentional fraud, "the insurer shall pay the whole amount mentioned in the policy or renewal upon which it receives a premium, in case of total loss, and in case of partial loss, the full amount thereof." Minnesota is unusual in reaching partial losses in the statute itself. Section 65A.04 then protects it: "Nothing in the preceding sections of this chapter shall be construed to limit the effect of or in any way modify or repeal section 65A.08."
The same section also deals with coinsurance by name. Under § 65A.08 subd. 5, "Any policy may contain a coinsurance clause, if the insured requests the same, in writing, of which fact such writing shall be the only evidence, and if, in consideration thereof, a reduction in the rate of premium is made by the company." A clause attached on those terms is "binding upon both the insured and the company," and "the actual cash value of the property so insured at the time of the loss, including the buildings, shall be the basis for determining the proper amount of the coinsurance, and the amount of loss, notwithstanding any previous valuation of the building."
So Minnesota's valued policy law does not remove a coinsurance clause either. What it gives you is two questions for the carrier: where is the written request for this clause, and what value was used, since subdivision 5 names actual cash value at the time of the loss as the basis.
⚠️ A scope flag we would rather raise than gloss over. Section 65A.08 sits in Minn. Stat. ch. 65A, headed "Fire and Related Insurance," alongside the Minnesota Standard Fire Insurance Policy at § 65A.01. Minnesota courts have confined other provisions of that chapter to fire losses, so whether § 65A.08 reaches a wind or hail claim on a homeowners policy is a question about the chapter's reach, not about the words. Treat it as settled for fire and open for other perils until your own file is reviewed.
South Dakota — SDCL § 58-10-10. Where a policy insures real property in South Dakota "against loss by fire, tornado, or lightning and the property insured is wholly destroyed, without criminal fault," the amount of insurance written "shall be taken conclusively to be the true value of the property insured and the true amount of loss and measure of damages."
Read that peril list closely, because it is the narrowest of the five: fire, tornado, or lightning. A hail loss is not on it. South Dakota also requires ninety days of seasoning where North Dakota requires sixty and Florida's statute has no waiting period, settles builder's risk and new residential construction on completed value, applies pro rata where two policies cover the same interest, and — the one that matters most for the next section — subdivision (7) states the section "does not apply to any claim for total loss to any building which is insured under a commercial blanket form with one amount covering two or more buildings."
Two things to take from all five. First, apart from Minnesota's wording on partial losses and Florida's fire-and-lightning subsection, these are total loss statutes, so on a partial loss the valuation fight is the whole game.
Second, even on a total loss, a valued policy law is not an automatic answer to a coinsurance penalty. Florida's says a coinsurance clause that meets § 627.701 still applies. Minnesota's permits one the insured requested in writing in exchange for a lower rate.
North Dakota's and South Dakota's sections do not mention coinsurance, and Wisconsin permits it in a separate statute, which leaves the outcome in those three states to the policy wording and that state's courts. What every one of these statutes does give you is a list of conditions, and conditions can be checked against your own policy and dates.
Associations and Blanket Policies Are Where This Bites Hardest
If you sit on a condominium or homeowners association board, coinsurance is a larger exposure for you than for any single homeowner, for three structural reasons.
Blanket limits drift. A single amount covering several buildings was set against construction costs at one point in time, and replacement costs have moved substantially in recent years while renewals often moved the limit by an inflation factor instead of a new valuation. The gap compounds quietly until a loss measures it.
Blanket forms can also sit outside the valued policy laws described above. Florida's does not apply where two or more buildings are insured under a blanket form for a single amount of insurance, under § 627.702(3)(b). South Dakota's expressly excludes a total loss to a building insured under a commercial blanket form covering two or more buildings, settling it on the policy's own replacement cost or actual cash value terms instead.
And the consequence of a coinsurance penalty on an association claim is not an abstraction. The shortfall between what the buildings need and what the carrier pays becomes a special assessment, divided among the members who elected the board.
Florida condominium boards have a statutory lever here that is worth knowing about before a loss rather than after. Under Fla. Stat. § 718.111(11)(a)2, the amount of adequate coverage for full insurable value or replacement cost "may be based on the replacement cost of the property to be insured, as determined by an independent insurance appraisal or an update of a previous appraisal," and that replacement cost "must be determined at least once every 3 years, at minimum."
That requirement cuts both ways, which is exactly why it is useful. A board holding a current independent appraisal has contemporaneous, third-party evidence of insurable value that competes directly with whatever the carrier produces after the loss.
A board that has let the three-year cycle lapse has no such evidence, and is relying on a number the other side chose. If your association's last appraisal is older than three years, that is a board action item this quarter — not a claim problem for later.
We handle association and master policy claims across all five states; the groundwork is on our HOA and condominium association claims page, and Florida boards specifically should read Florida HOA insurance claims.
From Our Files
The single most useful thing we have learned about building valuations is how far apart two competent people can land on the same structure.
On a Wisconsin fire claim in our files, nobody disputed that the fire happened or that it was covered. The carrier's consultant priced the rebuild, and we priced the same rebuild.
The two figures were not close. The file sat on that gap for months while everything else about the claim was agreed.
That is the fact worth carrying into your own file, because it is exactly the fact a coinsurance penalty depends on. The penalty is computed from a number someone chose, using a method and inputs they chose, after your building was damaged.
When the eventual review happened, the scope our estimate had included and theirs had not was conceded. Which tells you the first figure was never the only defensible one.
So when a carrier's valuation arrives looking authoritative, the question is not whether it is plausible. It is what it was built from. Ask for the worksheet.
We are not describing this file to suggest a typical result. Every claim turns on its own policy, its own damage and its own evidence, and the only honest claim we make about this one is what the file records.
What to Do When a Coinsurance Penalty Shows Up
- Find the percentage. Pull the declarations page and locate the coinsurance condition and the figure beside the building limit. If there is no coinsurance condition on the form, the penalty is being applied in error.
- Work out which penalty it is. Proportional reduction of the payment, or a move from replacement cost to actual cash value? Read the loss settlement condition, not the summary letter.
- Demand the valuation worksheet in writing. Ask for the insurable value used, the date it was determined, the method, and the inputs. A penalty asserted without a calculation is not a penalty you have to accept.
- Check what the form says counts as value. If foundations, excavation, underground pipes or land are inside the carrier's figure and excluded by your form, the required limit is overstated.
- Get your own replacement cost estimate from a source with no stake in the outcome, dated to the loss.
- Establish whether this is a total loss, and how the clause got onto the policy. On a total loss your state's valued policy law may change what the carrier owes, and the statutes above each have conditions you need to check against your own dates and limits. In Florida, look for the "Coinsurance contract" wording that § 627.701(1) requires. In Minnesota, ask for the written request that § 65A.08 subd. 5 requires.
- Do not let the dispute run your deadlines down. Proof of loss windows and suit limitation periods keep running while you argue about valuation. Diary them in writing.
Points two through five are the work. They are also the reason a valuation dispute usually needs someone who writes construction estimates for a living rather than someone who writes letters.
Frequently Asked Questions
What is a coinsurance penalty in property insurance?
It is a reduction the insurer applies to a covered claim because you carried less insurance than your policy's coinsurance condition required. Coverage is not denied. The insurer pays the proportion of your loss that your actual limit bears to the limit you should have carried: insurance carried divided by insurance required, times the loss, less your deductible. The required limit is a stated percentage of the property's value at the time of loss, most often eighty percent.
How is a coinsurance penalty calculated?
Divide the insurance you carried by the insurance the clause required, then multiply by the amount of the loss. The result is what the insurer pays before your deductible comes off. The required figure is the property's insurable value at the time of loss multiplied by the coinsurance percentage on your declarations page. The one input worth challenging is that value, because the insurer determines it after your loss using its own method.
Does homeowners insurance have a coinsurance clause?
Usually not under that name, but most homeowners forms do something similar. Instead of reducing the payment proportionally, they make replacement cost settlement conditional on insuring the dwelling to at least eighty percent of its full replacement cost. If you fall below that, the claim is settled at actual cash value instead, so depreciation comes off the whole loss rather than a fraction being withheld. This is policy form language and it varies between carriers, so the only reliable source is your own loss settlement condition.
Can a coinsurance penalty be challenged or reversed?
Yes, and the usual route is the valuation rather than the clause. The penalty depends on the insurer's opinion of what your building was worth at the time of loss, and an opinion of value can be wrong — through generic cost estimator inputs, through counting property the form excludes from insurable value, or through a valuation dated well after the loss. Ask for the worksheet in writing, get an independent replacement cost estimate dated to the loss, and if the two sides cannot agree, most policies contain an appraisal clause written for exactly this disagreement.
Does a coinsurance penalty apply to a total loss?
It can, and the answer depends on the state. Florida, Minnesota, Wisconsin, North Dakota and South Dakota each have a valued policy law making the amount of insurance written in the policy the measure of a total loss, but that does not automatically remove a coinsurance clause. Florida's statute says a total loss remains subject to a coinsurance clause that meets § 627.701, and Minnesota's § 65A.08 subd. 5 permits a coinsurance clause the insured requested in writing. The North Dakota and South Dakota sections do not mention coinsurance, so the answer there turns on the policy and that state's case law. Each statute also has conditions — Florida excludes blanket policies and losses caused partly by a noncovered peril, Wisconsin reaches only owner-occupied dwellings, South Dakota covers only fire, tornado and lightning, and North Dakota and South Dakota both require the policy to have been in force for a period before the loss. Check your own policy against the statute.
What is the difference between coinsurance and a deductible?
A deductible is a fixed amount you agreed to absorb on every claim, and it is subtracted from what the insurer would otherwise pay. A coinsurance penalty is a proportional reduction imposed because of how much insurance you bought, and it is calculated before the deductible is applied. You can face both on the same claim, and on a hurricane claim in Florida you can face a percentage deductible as well.
Why did my insurance company say my building was worth more than I insured it for?
Because the valuation that drives a coinsurance penalty is performed after the loss by the insurer, not at the time the policy was written. Construction costs have risen sharply in recent years, so a limit that met the coinsurance requirement when it was set can fail it years later without anyone changing anything. That is a genuine exposure. It is also why the carrier's post-loss figure deserves the same scrutiny as its damage estimate.
How can a condo or homeowners association avoid a coinsurance penalty?
Keep the insurable value current and documented. For Florida condominium associations, § 718.111(11)(a)2 provides that adequate coverage may be based on replacement cost determined by an independent insurance appraisal, and that the replacement cost must be determined at least once every three years. A board holding a current appraisal has independent evidence of value to put against the carrier's number. A board relying on an inflation factor applied at renewal has none, and the shortfall after a loss becomes a special assessment on the members.
Who pays the difference when a coinsurance penalty is applied?
You do. That is the entire function of the clause — it makes the policyholder a co-insurer of the loss in proportion to the coverage they did not buy. On a residential claim the shortfall comes out of the owner's pocket or out of the scope of the repair. On an association claim it usually becomes a special assessment. Which is why establishing whether the penalty was correctly calculated is worth doing before anyone accepts the payment.
Get the penalty checked before you accept the payment
A coinsurance reduction is a number, and numbers can be audited. If one has been applied to your claim in Minnesota, Wisconsin, Florida, North Dakota or South Dakota, send us the settlement worksheet and the declarations page and we will tell you whether the valuation behind it stands up. No upfront fee — our fee is agreed in writing before we begin and comes out of what we recover.
Related Reading
- The insurance appraisal clause — the process that exists for the one thing a coinsurance penalty always comes down to, which is two sides disagreeing about a construction number.
- Recoverable depreciation — what happens to your money if the coinsurance condition pushes you from replacement cost down to actual cash value.
- Will insurance cover a 20-year-old roof — where the eighty-percent insure-to-value condition shows up most often on a residential claim.
- Denied versus underpaid insurance claims — a coinsurance penalty is the purest form of underpayment, since nothing about your coverage was ever in dispute.
- Commercial claim support — coinsurance conditions are standard on commercial property forms, which is where the proportional penalty does the most damage.
- Coverage gap calculator — check the distance between your building limit and current replacement cost before a loss measures it for you.
Sources
- Fla. Stat. § 627.702 — Florida's valued policy law; (1)(a) total loss, (1)(b) the covered-plus-noncovered peril carve-out, (2) partial losses by fire or lightning, (3)(b) the blanket form exclusion, (4) losses under (1) and (2) remain subject to a coinsurance clause under § 627.701 (verified 2026-10-12)
- Fla. Stat. § 627.701(1) — the three conditions for a coinsurance provision in a Florida property policy, including the "Coinsurance contract" wording (verified 2026-10-12)
- Fla. Stat. § 627.7011(3)(a) — replacement cost settlement and the total-loss holdback bar, which points to § 627.702 (verified 2026-10-12)
- Fla. Stat. § 718.111(11)(a)2 — condominium association property insurance; replacement cost by independent appraisal, re-determined at least every 3 years (verified 2026-10-12)
- N.D.C.C. § 26.1-39-05 — face of policy paid on a total loss from any covered cause of loss, with the 60-day and 25%-increase conditions (verified 2026-10-12)
- Wis. Stat. § 632.05(2) — total loss of an owner-occupied dwelling taken conclusively to be the policy limits (verified 2026-10-12)
- Wis. Stat. § 631.45(2) — property coinsurance clauses permitted (verified 2026-10-12)
- Wis. Stat. § 631.43(1) — the pro rata statute, which governs where two policies cover the same loss (verified 2026-10-12)
- Minn. Stat. § 65A.08 subd. 2(a) and subd. 5, and § 65A.04 — the whole amount mentioned in the policy, the conditions for a coinsurance clause, and the section preserving § 65A.08 (verified 2026-10-12). All sit in Minn. Stat. ch. 65A, "Fire and Related Insurance"
- SDCL § 58-10-10 — fire, tornado or lightning; policy amount taken conclusively to be true value, with the 90-day condition and the commercial blanket exclusion at (7) (verified 2026-10-12)
- Cambier v. Integrity Mutual Insurance Co., 2007 WI App 200; Seider v. O'Connell, 2000 WI 76; Wegner v. West Bend Mutual Insurance Co., 2007 WI App 18 — case law, not statute. These set the scope of Wis. Stat. § 632.05(2)
- The 80% replacement cost condition in homeowners forms and the coinsurance condition in commercial property forms are policy form language, not statute. No state law imposes either, and they vary between carriers and between editions of the same form. The Florida, Minnesota and Wisconsin statutes above set out when a coinsurance clause is permitted
This page is general information about how property insurance valuation and coinsurance conditions work. It is not legal advice, and it does not create a professional relationship. Shoreline Public Adjusters, LLC is a licensed public adjusting firm and is not a law firm. Licensed in Minnesota (MN 40962416), Wisconsin (WI 21156868), Florida (FL G199012), North Dakota (ND 3004392416), and South Dakota.
Shoreline Public Adjusters, LLC
780 Fifth Avenue South
Suite #200
Naples, FL 34102
Email: hello@teamshoreline.com
Phone: 954-546-1899
Fax: 239-778-9889