TL;DR — Recoverable Depreciation on an Older Roof: The First Check Is Not the Whole Claim
- Age decides the payout, not the coverage. A storm-damaged 20-year-old roof is covered the same as a new one. What changes is how much the insurer holds back.
- On a replacement cost policy, the holdback is yours to claim. The standard homeowners form pays no more than actual cash value until the repair is actually done, then settles the rest.
- Florida puts that in statute. Fla. Stat. 627.7011(3)(a) makes the insurer pay at least actual cash value up front and the remaining amounts as the work is performed.
- Florida also limits roof-age underwriting. Under 627.7011(5), a policy can't be refused or non-renewed solely because a roof is under 15 years old, and an inspection showing 5 years of life left protects an older roof.
- In Minnesota, replacement cost has to include code. Minn. Stat. 65A.10 subd. 1 requires replacement cost insurance to cover repairs that meet the minimum code the state or local authority requires.
Your Roof's Age Doesn't Decide Coverage. It Decides the First Check.
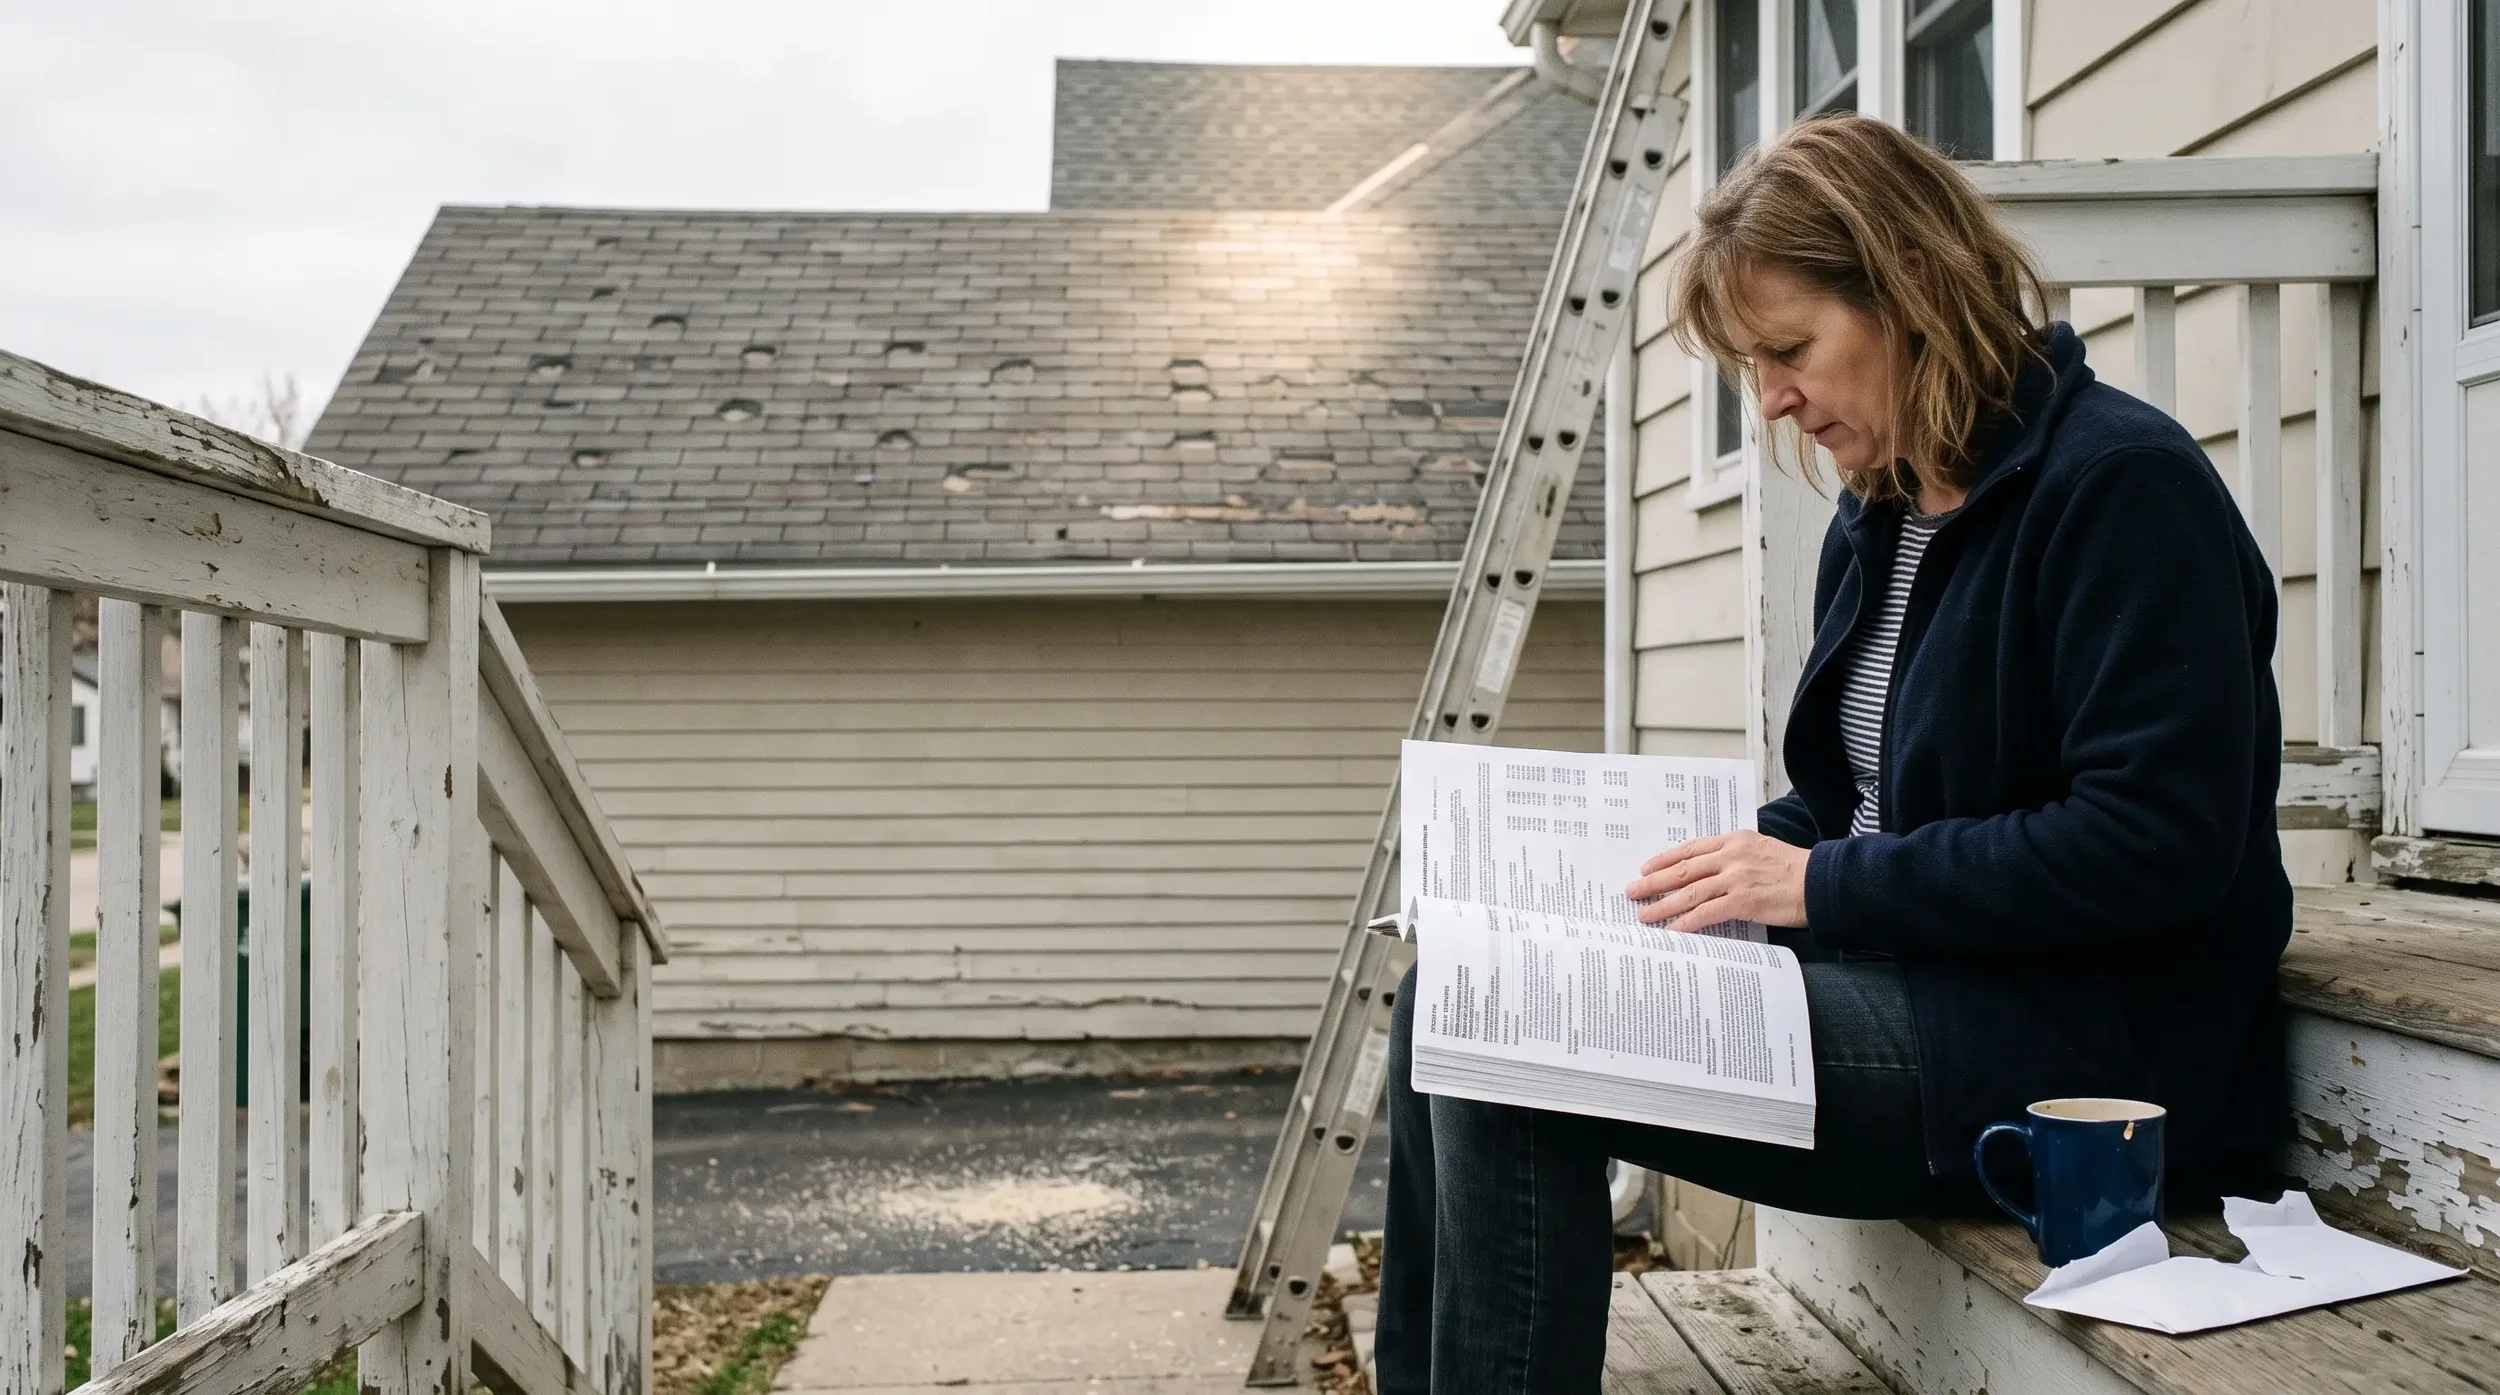
A hailstorm doesn't care how old the shingles are, and neither does the covered-peril question. Storm damage to a 20-year-old roof is covered the same way it is on a 5-year-old roof.
What changes is the math after the word "approved." The insurer subtracts depreciation for the roof's age and condition, and the first check arrives smaller than the repair.
That subtraction is often recoverable, which means the insurer still owes it once the work is done. Homeowners lose that money by not knowing it exists, not by being denied.
Actual Cash Value, Replacement Cost, and the Holdback
The standard homeowners form (ISO HO-3, the form many policies follow) settles building losses at replacement cost without deduction for depreciation, as long as the building is insured for at least 80 percent of its full replacement cost. It then pays the least of three numbers: the policy limit, the replacement cost of the damaged part, or the amount actually spent on the repair.
The holdback lives one line below that. The form says the insurer will pay no more than the actual cash value of the damage until the repair or replacement is actually complete, and will settle the rest once it is.
So the first check is the depreciated number, by design. The remainder, the recoverable depreciation, is released after the roof is replaced and the final invoice is in.
Two details in the same clause are worth knowing:
- Small losses skip the holdback. If the repair costs less than 5 percent of the building's insured amount and less than $2,500, the form settles without waiting for the work.
- You can elect actual cash value and change your mind. The form lets you claim on an actual cash value basis and then claim the rest, if you tell the insurer within 180 days of the date of loss.
Read your own declarations page before assuming which one applies to you. A policy can insure the dwelling at replacement cost and still carry an endorsement that pays roof surfaces at actual cash value, and that endorsement is where an older roof usually loses its holdback.
How the Holdback Actually Gets Released
Insurers do not release recoverable depreciation on their own. It takes a completed repair and paperwork.
1. Get the insurer's estimate, line by line. The depreciation is shown per line item, not as one lump, and that is where the argument lives.
2. Compare the scope to a real reroof. A tear-off on an older roof usually brings in decking, underlayment, drip edge, starter strip and ridge, none of which appear if the adjuster scoped an overlay.
3. Do the work, keep every invoice. The form settles the rest based on what was actually spent, so the final invoice is the trigger.
4. Submit a supplement with the final invoice. Ask specifically for the release of recoverable depreciation, and include any line items that were added during the tear-off.
5. Watch the deadlines. Policies limit how long you have to claim the holdback after the loss, and that limit is in your policy, not in the adjuster's email.
What Changes by State
Florida. Fla. Stat. 627.7011(3)(a) requires the insurer, on a replacement cost dwelling loss, to pay at least actual cash value less the deductible up front and then pay the remaining amounts as the work is performed. If a roof deductible under s. 627.701(10) applies, the insurer may hold the roof payment at actual cash value until it gets reasonable proof you paid that deductible, which the statute says can be a canceled check, money order receipt, credit card statement or an executed payment plan.
Roof age also has its own Florida rules. Under 627.7011(5), an insurer may not refuse to write or renew a policy solely because the roof is less than 15 years old, and for a roof 15 years or older it must let you get an inspection by an authorized inspector at your expense first. If that inspection shows the roof has 5 or more years of useful life left, roof age alone is not a reason to refuse the policy.
Florida also has a matching rule. Fla. Stat. 626.9744(2) says that when replacement items do not match in quality, color or size, the insurer shall make reasonable repairs or replacement in adjoining areas, weighing cost, the uniformity achievable, and the remaining useful life of the undamaged portion.
Minnesota. Minn. Stat. 65A.10 subd. 1 says that where an insurer offers replacement cost insurance, the coverage must pay to replace, rebuild or repair in accordance with the minimum code required by state or local authorities. On an older roof that matters, because the code items are exactly what gets left out of a repair-only scope.
One of those items is specific to this climate: Minnesota's residential code requires an ice barrier running from the lowest edge of the roof to at least 24 inches inside the exterior wall line. Minnesota's matching authority is case law rather than a statute, and it is Cedar Bluff Townhome Condominium Ass'n v. American Family, 857 N.W.2d 290 (Minn. 2014).
Wisconsin. There is no Wisconsin matching statute or rule, so a matching argument in Wisconsin rests on the wording of your own policy. Wisconsin's contribution is timing: Wis. Stat. 628.46 treats a payment as overdue 30 days after the insurer is furnished written notice of a covered loss and the amount of it, and puts simple interest of 7.5 percent a year on money that runs late.
On a holdback, the final invoice is what furnishes that amount. Send it in writing, keep the date, and the 30 days are running from something you can prove.
Depreciation Is an Estimate, Not a Measurement
Depreciation on a roof is usually applied on a straight-line schedule: the shingle's rated life, the roof's age, a percentage. It is a convention, not a finding about your roof.
Condition is what the policy actually turns on, and condition is arguable. Maintenance records, prior inspection reports, photos from before the storm and a roofer's statement on remaining useful life all push against a schedule that assumed steady decline.
Watch for depreciation applied twice as well: an age-based percentage plus a separate wear-and-tear deduction on the same line. Ask which policy language supports the second one.
From Our Files: The First Payment Was Not the Total
This one comes from a hail claim rather than an old-roof dispute, and we can only describe the part the file documents.
The first payment on that claim was not the whole claim. A second payment followed it, and the total landed about 40 percent above the first check.
The file does not record what moved it, so we are not going to guess. What it does show is the shape of these claims: the first number is a starting point, and the money that shows up later is the part homeowners most often leave behind.
An older roof claim runs on that same shape, with one difference. The later money is usually the depreciation the insurer already told you it was holding back, and it is released on your paperwork, not on its schedule.
Mistakes That Cost an Older Roof Claim Real Money
1. Treating the first check as the settlement. On a replacement cost policy the first check is the depreciated number, and the rest is released after the work. What to do instead: find the recoverable depreciation line on the estimate and put a date on your calendar to claim it.
2. Not checking whether the roof is on its own endorsement. A dwelling can be insured at replacement cost while the roof surface sits on an actual cash value endorsement. What to do instead: read the declarations page and the endorsement list before you argue about the number.
3. Accepting a repair scope on a roof that needs a tear-off. Overlay scopes leave out decking, underlayment, drip edge and code items. What to do instead: get a line-item estimate from a roofer for a full replacement and compare the two side by side.
4. Letting the depreciation percentage go unchallenged. A schedule is a starting assumption about condition, not a measurement of your roof. What to do instead: document maintenance and remaining useful life, and ask the insurer for the basis of the rate it used.
5. Doing the work and never sending the final invoice. The holdback is settled on what was actually spent. What to do instead: send the final invoice with a written request to release recoverable depreciation, and keep a copy. Our ACV vs RCV calculator shows what the holdback on your own numbers looks like.
Frequently Asked Questions About Insurance on Older Roofs
Will insurance cover a 20-year-old roof?
Storm damage to a 20-year-old roof is covered the same as damage to a new one, as long as the cause is a covered peril. Age changes the payout rather than the coverage, because the insurer deducts depreciation for the roof's age and condition. On a replacement cost policy that deduction is usually recoverable after the repair is complete.
What is recoverable depreciation on a roof claim?
It is the amount the insurer subtracts from the replacement cost when it issues the first check, and then pays after the work is done. The standard homeowners form pays no more than actual cash value until the repair or replacement is actually complete, and settles the remainder afterward. It is released on a final invoice, not automatically.
How do I get recoverable depreciation released?
Complete the repair, then send the insurer the final invoice with a written request to release the recoverable depreciation. Include any line items that were added during the tear-off, such as decking or code-required underlayment. In Florida, Fla. Stat. 627.7011(3)(a) requires the insurer to pay the remaining amounts as the work is performed and expenses are incurred.
What is the actual cash value of an older roof?
Actual cash value is the replacement cost minus depreciation for age and condition. Insurers usually apply a straight-line schedule based on the shingle's rated life, which is a convention rather than a measurement of your roof. Maintenance records, prior inspections and a roofer's opinion on remaining useful life are what move that number.
Can a Florida insurer drop my policy because of my roof's age?
Not solely for age if the roof is under 15 years old, under Fla. Stat. 627.7011(5)(b). For a roof 15 years or older, the insurer must let you get an inspection by an authorized inspector at your own expense before requiring replacement as a condition of coverage, and it may not refuse the policy solely on roof age if that inspection shows 5 or more years of useful life remaining.
Does insurance have to pay for code upgrades on an older roof?
In Minnesota, where an insurer offers replacement cost insurance, Minn. Stat. 65A.10 subd. 1 requires the coverage to pay for repair, rebuilding or replacement that meets the minimum code required by state or local authorities. That reaches items an older roof often lacks, such as the ice barrier the residential code requires from the roof edge to 24 inches inside the exterior wall line. Florida handles code separately through law and ordinance coverage under Fla. Stat. 627.7011.
What if the new shingles don't match the rest of the roof?
In Florida, Fla. Stat. 626.9744(2) requires the insurer to make reasonable repairs or replacement in adjoining areas when replaced items do not match in quality, color or size, considering cost, achievable uniformity and remaining useful life. Minnesota's matching authority is case law, Cedar Bluff Townhome Condominium Ass'n v. American Family, 857 N.W.2d 290 (Minn. 2014). Wisconsin has no matching statute or rule, so the argument there rests on your policy's wording.
Should I hire a public adjuster for an older roof claim?
It helps most when the scope and the depreciation are both in question. A licensed public adjuster reads the estimate line by line, prices a full tear-off with the code items an older roof triggers, documents condition against the depreciation schedule, and handles the supplement that releases the holdback. That work is easiest before the roof is replaced.
Before You Cash the First Check
An older roof claim is rarely lost on coverage. It is lost in the depreciation line and in a scope that assumed a patch.
A review of the estimate, the declarations page and the endorsement list costs nothing, and it is most useful before the repair is scheduled. Our hail damage claim help covers roof claims in Minnesota, Wisconsin and Florida.
Send the estimate to Shoreline Public Adjusters and we will read it against your declarations page for free. We represent policyholders only, and there is no upfront fee.
Related Reading
- What to do if insurance denied your roof claim — when the answer is no rather than not enough.
- An underpaid insurance claim — how to prove the gap when the check falls short.
- The insurance appraisal clause — the option when the only disagreement is the amount.
Shoreline Public Adjusters, LLC is licensed in Florida (FL G199012), Minnesota (MN 40962416), Wisconsin (WI 21156868), North Dakota (ND 3004392416), and South Dakota.
Shoreline Public Adjusters, LLC
780 Fifth Avenue South
Suite #200
Naples, FL 34102
Email: hello@teamshoreline.com
Phone: 954-546-1899
Fax: 239-778-9889