
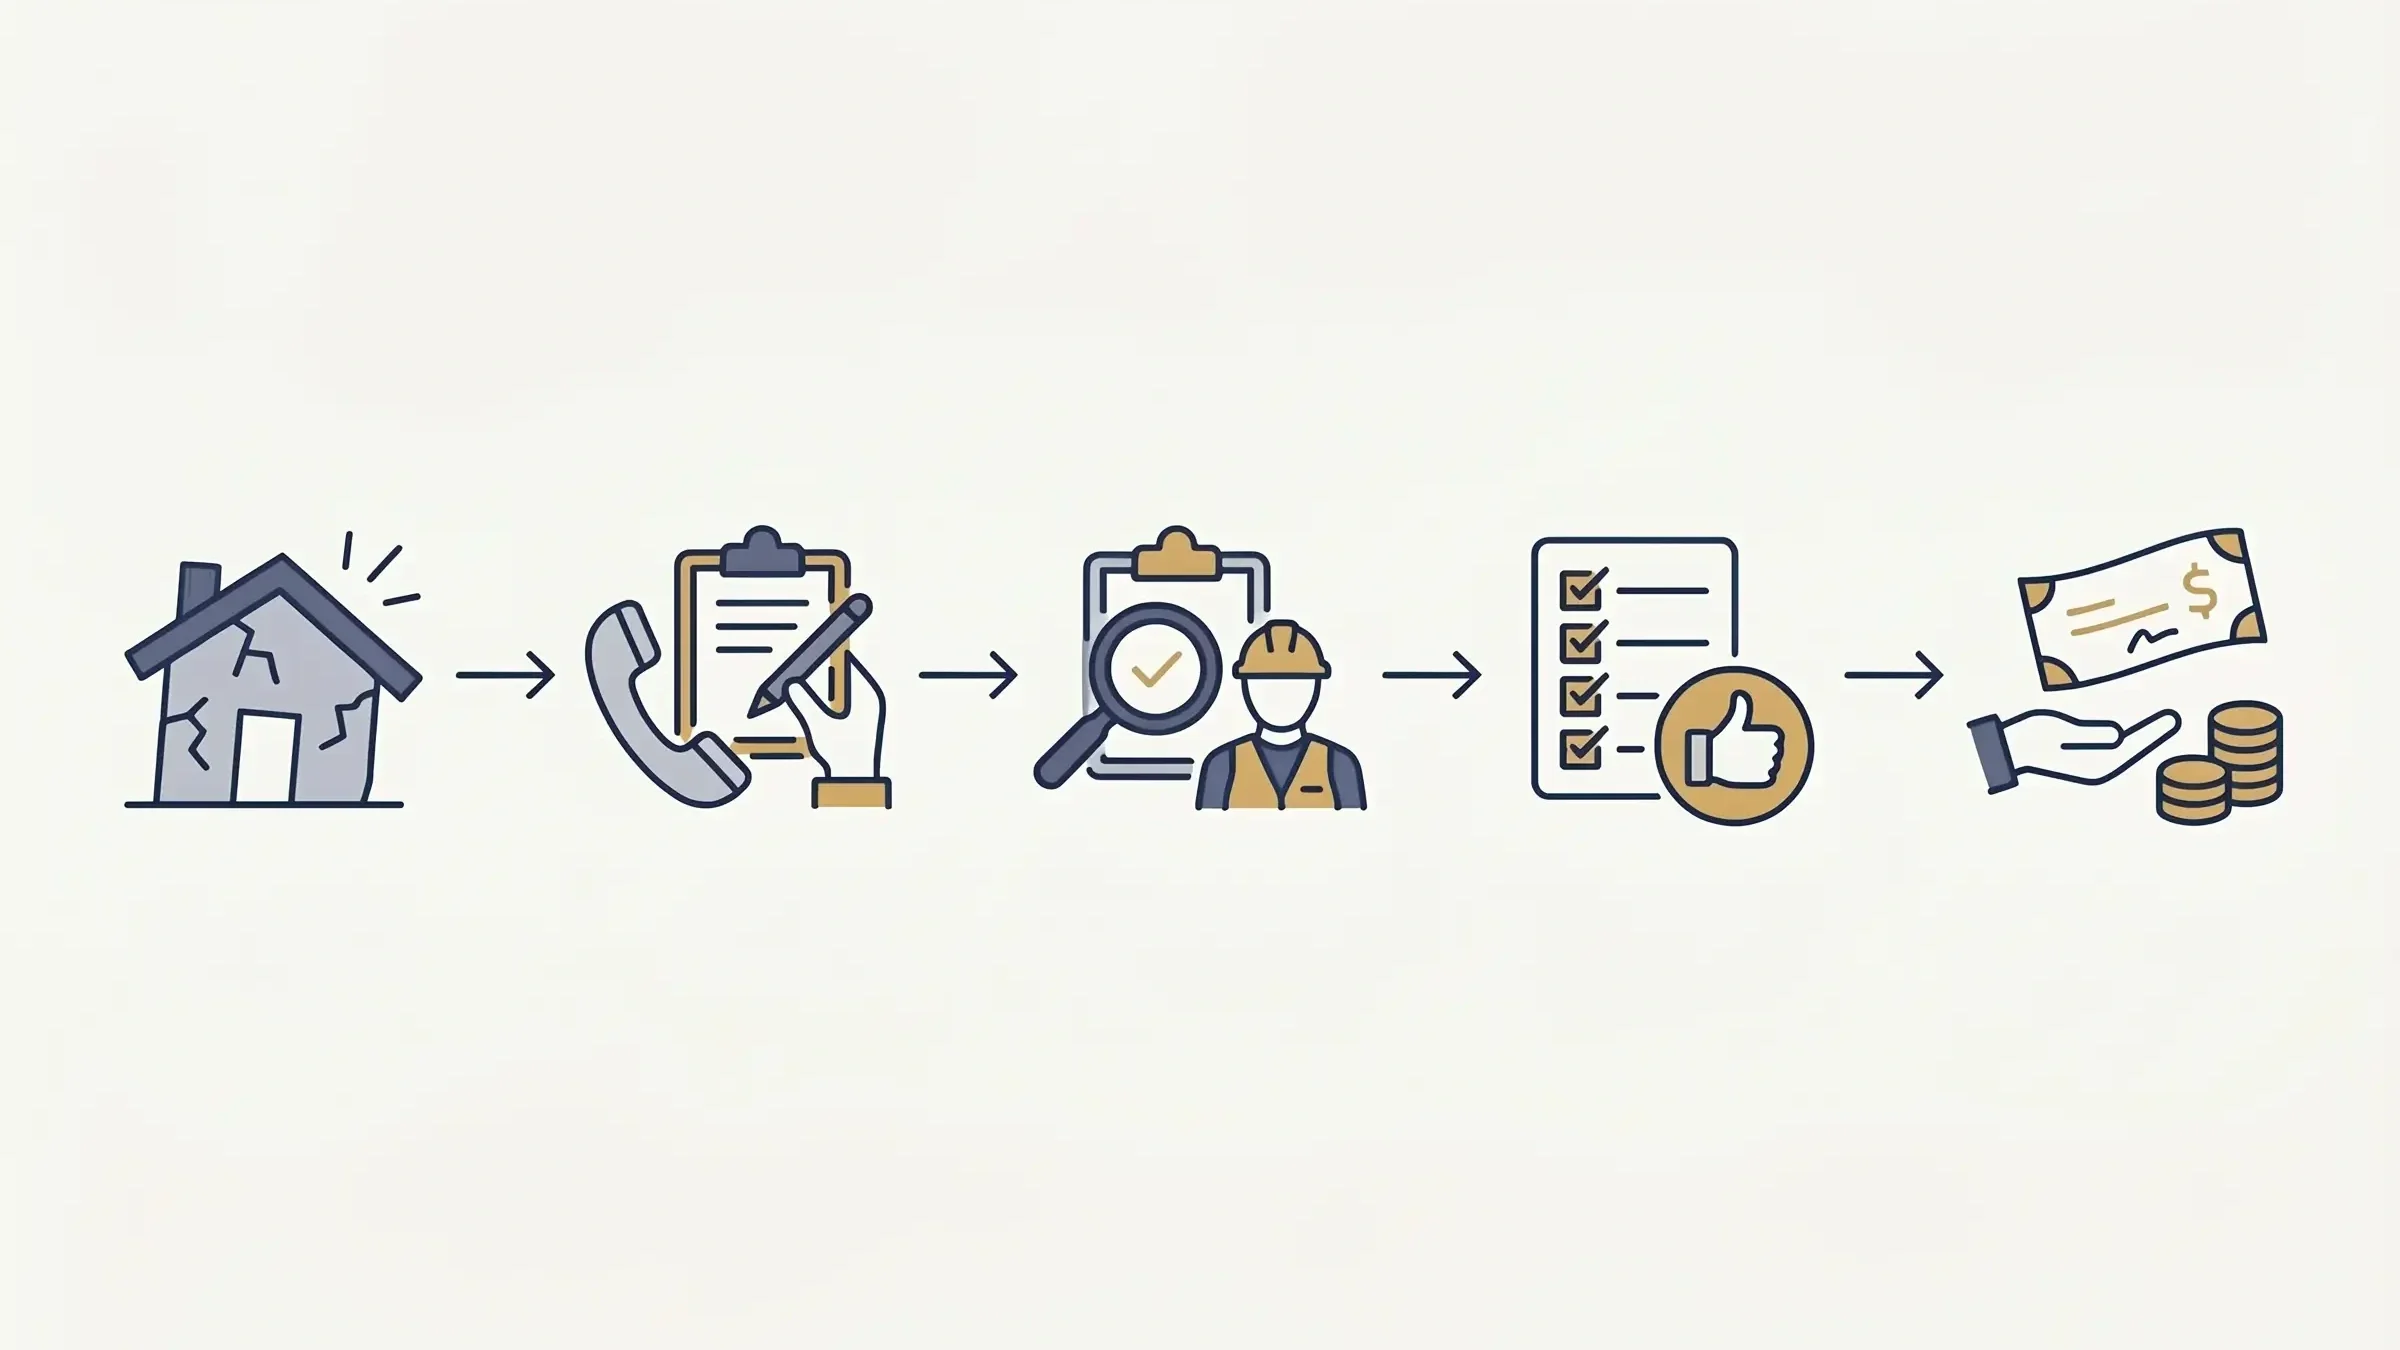
What public adjusters actually do, step by step
"Public adjuster" is one of those professional titles that doesn't tell you much about the actual work. Here's what we do on a typical residential claim, in order:
- Free initial review. You send us your denial letter, settlement offer, or just the facts of your loss. We tell you whether we think we can help — and whether the math makes sense for you to hire a PA.
- Policy and claim file analysis. We read your full policy (most homeowners haven't), the insurer's claim file, and any inspection reports. This usually surfaces coverages the insurer hasn't applied or exclusions that don't actually apply to your loss.
- Independent damage assessment. We inspect the property ourselves — sometimes with engineers, industrial hygienists, or contractors. Our scope of loss often differs significantly from the insurer's.
- Documentation and proof of loss. We assemble photos, contractor estimates, expert reports, and the formal proof-of-loss document the insurer requires. Most underpayments happen because the homeowner couldn't document the full scope.
- Claim negotiation. We negotiate directly with the insurance company's adjuster. This is where most of the recovery happens — they have a number, we have a number, and we work toward a settlement.
- Escalation if needed. If negotiation stalls, the policy's appraisal clause, a complaint to the state insurance department, or a referral to an attorney are the routes available. Which one fits depends on the policy and the state.
- Settlement and payout. The insurer issues the check. Our fee is a percentage of the claim payments you receive, and there is no upfront fee.
How long this takes depends on the loss, the state, and how much of it is disputed. A single-peril claim with an undisputed cause moves far faster than a denied claim on a multi-trade loss. What we can tell you at the start is which of those two your claim looks like.
When hiring a public adjuster makes sense (and when it doesn't)
Counter-intuitive truth: not every claim needs a public adjuster. We tell people that on first calls. Here's the honest breakdown.
When a PA usually pays for itself
- The claim is denied. A denial is a position, not a verdict. Ask, in writing, for the exact policy provision it rests on — in Minnesota the insurer is required to give you that, under Minn. Stat. § 72A.201 subd. 4(11). The answer is frequently where the file turns.
- The settlement offer doesn't match the repair bid. If the insurer's number and your contractor's number are far apart and nobody can explain why, the gap is worth examining.
- The loss is large. Bigger claims have more components, more places for scope to be missed, and more room for a contingency fee to be worth paying. The smaller the claim, the harder that math is to justify.
- The damage is complex. Multiple perils (wind plus flood, water plus mold), structural damage, code-required upgrades, or claims involving high-value contents — all benefit from PA expertise.
- The insurer is dragging the claim. In Florida, Fla. Stat. § 627.70131(1)(a) requires an insurer to review and acknowledge a communication about a claim within 7 calendar days, and (7)(a) requires it to pay or deny within 60 days after receiving notice of an initial, reopened or supplemental property claim. Minnesota, Wisconsin, North Dakota and South Dakota each set their own clock. If yours has passed, that is a concrete thing to raise.
When a PA probably isn't worth it
- The claim is small. On a minor loss, a contingency fee may not produce enough net benefit to justify representation. Compare the whole loss against your deductible first.
- The insurer is paying full freight on the first offer. If the offer matches your contractor estimates and there's no dispute, you don't need representation.
- You've already cashed the settlement check. Once you've signed a release, the claim is typically closed. There are exceptions (supplemental claims), but the leverage is mostly gone.
The one study people cite, and what it actually says: Florida's Office of Program Policy Analysis and Government Accountability studied this in Report 10-06, January 2010. On non-catastrophe claims filed with Citizens Property Insurance Corporation in 2008 and 2009, policyholders who used a public adjuster received a median payment of $9,379 against $1,391 for those who did not — a difference of 574%. Four things belong with that number every time it is quoted. Those are gross figures, before the adjuster's fee, so the net gain is smaller. The report's own title says public adjuster representation extends the time to reach a settlement. It looked at one insurer, in one state, on claims now more than fifteen years old. And public adjusters are typically hired on the harder claims — denied, partial, disputed — which is a selection effect, not a multiplier anyone should expect on a straightforward loss.
How public adjusters get paid, and what each state allows
Every state regulates public adjuster compensation differently, and the differences are larger than most people expect. Here is what the statutes say in the five states we work in. Each was read from the statute on September 30, 2026.
| State | What the statute sets | Citation |
|---|---|---|
| Florida | 20% of claim payments or settlements, exclusive of attorney fees and costs. 10% for claims based on events subject to a Governor's declaration of a state of emergency, for claims made during the year after the declaration. 1% where the insurer pays or commits in writing to pay the policy limit within 14 days of the date of loss. On a reopened or supplemental claim the fee may be based only on payments obtained after the contract is signed. | Fla. Stat. § 626.854(11)(a)–(b) |
| Wisconsin | 10% cap where the claim is due to a catastrophic disaster (a presidential or gubernatorial emergency declaration). Otherwise no percentage cap, but: an hourly rate only if the insurer pays the policy limit within 5 business days of the loss being reported; no compensation demanded before the insured is paid; and on installment payments the fee is prorated across every check, not taken from the first. | Wis. Stat. § 629.05(3)–(6) |
| North Dakota | A public adjuster may not accept compensation equal to or more than 10% of a settlement resulting from a catastrophic disaster, and may not take any fee, retainer or deposit before settlement unless the loss is handled on a time-plus-expense basis. A contract may not let the adjuster collect the entire fee from the first check. | N.D. Cent. Code ch. 26.1-26.8 |
| Minnesota | No percentage cap in statute. What Minnesota regulates instead is the contract: you may cancel within 72 hours of signing, the adjuster must hand you a boldface notice of that right and a detachable cancellation form, and any payments must be returned within ten days of cancellation. | Minn. Stat. § 72B.135 subd. 1–3 |
| South Dakota | South Dakota has no public adjuster licensing chapter, so there is no state fee cap to cite. The work is governed by the contract and by the unfair claim practice rules that apply to insurers. | — |
Three things to know that aren't in the table:
- No upfront fee. A public adjuster who asks for a retainer or an hourly payment before a settlement is outside the norm, and in North Dakota outside the statute. Ask what the fee is and when it is payable before you sign.
- Get the percentage, and what it attaches to, in writing. The rate matters less than the base. On a supplemental claim, whether the fee is charged on the whole recovery or only on new money after the contract is signed can change the number substantially.
- In Florida, a contingency-fee public adjuster cannot serve as a "disinterested" appraiser. The Florida Supreme Court held in Parrish v. State Farm Florida Insurance Co., No. SC21-172 (Feb. 9, 2023), that "an appraiser cannot be 'disinterested' if he or she, or a firm in which he or she has an interest, is to be compensated for services as a public adjuster with a contingency fee." That was a residential Hurricane Irma claim, so the rule reaches property appraisal, not just auto work. Where a policy calls for a disinterested appraiser, the appraiser has to be engaged separately from the contingency arrangement.
The arithmetic is worth doing before you sign anything. On a $50,000 Florida settlement outside an emergency declaration, a 20% fee is $10,000. On a claim from a Governor-declared emergency in the year after the declaration, the same settlement carries a $5,000 fee. In Wisconsin a catastrophe claim is capped at 10%. Minnesota sets no cap, which makes the written percentage the only thing protecting you.
Public adjuster vs. insurance adjuster
The most common confusion is not about fees. It is about who each adjuster is working for, and that one is not a matter of opinion — it is written into the statutory definitions. Minn. Stat. § 72B.02 subd. 6 defines a public adjuster as a person acting "on behalf of the insured." Two subdivisions earlier, subd. 5 defines an independent adjuster as a person who "contracts for compensation with insurers or self-insurers." Wisconsin goes further and excludes anyone who "represents an insurer in negotiations" from the definition of public adjuster entirely, at Wis. Stat. § 629.01(5)(f).
There are three kinds of adjuster who can show up on a property claim, and two of them are paid by your insurer. We set the statutory definitions side by side here, along with what the carrier's adjuster still owes you.
Public adjuster vs. attorney vs. doing it yourself
Three common questions we get on first calls:
"Should I just file the claim myself?"
For straightforward small claims, yes — that's often the right answer. The insurance claims process is designed to be navigable by homeowners. Mitigate the damage, document everything, file promptly, follow up if the offer is too low.
The problem isn't whether you can file your own claim. It's whether you'll get paid in full. If you're not equipped to push back with documentation and policy analysis, the gap between what you collect and what your claim is worth can be substantial.
"Should I hire a lawyer instead?"
Lawyers are the right call when you need to sue. Bad-faith insurance lawsuits are real causes of action, and good insurance attorneys win them. But litigation is slow, and many claim disputes resolve through negotiation before a lawsuit becomes necessary.
The usual sequence is a public adjuster first, a complaint to the state insurance department as parallel pressure, then an attorney if both fail. We refer cases to attorneys when the insurer's conduct warrants it, and we coordinate with their counsel. Nothing here is legal advice, and a lawyer is the right person to tell you whether you have a claim against your insurer.
"Can I do both?"
Yes — and it often makes sense on large or complex claims. Public adjusters handle the claim documentation and negotiation; attorneys pursue the legal remedies when negotiation fails. The documentation built during the claim becomes the foundation of anything that follows.
How to verify a public adjuster is licensed
Unlicensed people do show up in disaster zones, collect money and disappear. Verify the license before you sign anything. Every state that licenses public adjusters publishes a free lookup.
Florida
Search at the Florida Department of Financial Services license lookup. Confirm an active public adjuster license and check for disciplinary actions on record.
Minnesota
Use the Minnesota Department of Commerce licensing lookup. Public adjusters in Minnesota must be individually licensed.
Wisconsin
Use the Wisconsin Office of the Commissioner of Insurance lookup.
North Dakota
The North Dakota Insurance Department's public adjuster page explains the license and links its licensee lookup.
South Dakota
South Dakota does not license public adjusters, so there is no state lookup to check. Verify the adjuster's license in a state that does issue one, and read the contract carefully. The South Dakota Division of Insurance handles complaints about claim handling.
Our credentials: Shoreline Public Adjusters, LLC is licensed in Florida (#G199012), Minnesota (#40962416), Wisconsin (#21156868) and North Dakota (#3004392416), and works in South Dakota, which issues no public adjuster license. Verify any of these directly through the state lookups above before working with us.
Red flags to walk away from
- Asks for any upfront fee, retainer, or hourly payment
- Won't show you the contract before pressuring you to sign
- Promises a specific dollar recovery before reviewing your claim
- Solicits door-to-door immediately after a disaster
- License number can't be verified through the state lookup
- Won't put the fee percentage, and what it is charged on, in writing
What to do next
If you have an active claim — denied, underpaid, or just not feeling right — get a free review before you accept any offer or sign any release. Reviews are no-obligation. If your claim is straightforward and the insurer is paying full freight, we'll tell you that.
If you don't have an active claim but want to understand your policy before you need to file one, that's also a free conversation. Most homeowners haven't read their policies and don't know what's covered until something goes wrong.
Get a free claim review
Call (954) 546-1899 or use the form. We'll tell you whether a public adjuster can help — including when the answer is no. There is no upfront fee.
Start your free review →Frequently asked questions
Is a public adjuster the same as an insurance adjuster?
No, and the difference is in the statutes rather than in anyone's marketing. Minn. Stat. § 72B.02 subd. 6 defines a public adjuster as someone acting "on behalf of the insured," while subd. 5 defines an independent adjuster as someone who "contracts for compensation with insurers or self-insurers." Wisconsin excludes anyone who represents an insurer from the definition of public adjuster entirely, at Wis. Stat. § 629.01(5)(f). A public adjuster is hired by the policyholder and paid a percentage of what the claim pays.
How much does a public adjuster cost in Florida?
Fla. Stat. § 626.854(11)(b) caps public adjuster compensation at 20% of claim payments or settlements, exclusive of attorney fees and costs, and at 10% for claims based on events subject to a Governor's declaration of a state of emergency, for claims made during the year after the declaration. A third cap of 1% applies where the insurer pays or commits in writing to pay the policy limit within 14 days of the date of loss. There is no upfront fee.
Do the fee caps work the same way in every state?
No. Wisconsin caps catastrophe claims at 10% under Wis. Stat. § 629.05(6) and separately requires the fee to be prorated across every check rather than taken from the first. North Dakota bars compensation equal to or more than 10% on a catastrophic disaster claim and bars any fee before settlement. Minnesota sets no percentage cap at all but gives you 72 hours to cancel the contract under Minn. Stat. § 72B.135 subd. 1. South Dakota has no public adjuster chapter.
Can a public adjuster serve as the appraiser on my claim?
In Florida, not if they are working on a contingency fee. The Florida Supreme Court held in Parrish v. State Farm Florida Insurance Co., No. SC21-172 (Feb. 9, 2023), that an appraiser cannot be "disinterested" if he or she, or a firm they have an interest in, is compensated for public adjusting with a contingency fee. That case arose from a residential hurricane claim, so it applies to property appraisal generally where the policy requires a disinterested appraiser.
When is it too late to hire a public adjuster?
In most cases, before you've cashed the final settlement check. Once you sign a release and accept payment, the claim is typically closed. Your policy's own deadlines and your state's suit-limitation period also bind you, so earlier is easier — scope is far simpler to prove before repairs are made and wet materials are thrown out. If you're unsure, ask for a free review before accepting any offer.
Will hiring a public adjuster slow down my claim?
It can, and the honest answer is that it depends on the claim. The one substantial study on this point, Florida OPPAGA Report 10-06 (January 2010), found that public adjuster representation on Citizens claims filed in 2008 and 2009 extended the time to reach a settlement while increasing payments. A claim that is being actively disputed takes longer than one being paid without argument, whoever is handling it.
Related reading
Shoreline Public Adjusters, LLCEmail: hello@teamshoreline.com
Phone: 954-546-1899
Fax: 239-778-9889