TL;DR — Public Adjuster vs Insurance Adjuster
- The difference is written into the law, not into anyone's marketing. Four of the five states we work in define a public adjuster as someone who acts on behalf of the insured. Wisconsin goes further and excludes anyone who represents an insurer.
- There are three kinds of adjuster on a property claim, and two of them are paid by your insurer: the staff adjuster it employs, the independent adjuster it contracts with, and the public adjuster you hire.
- "Independent" describes the employment arrangement, not the loyalty. Minn. Stat. § 72B.02 subd. 5 defines an independent adjuster as someone who "contracts for compensation with insurers or self-insurers."
- The carrier's adjuster still owes you duties, and they are enforceable. Every one of our five states makes specific claim-handling failures an unfair practice.
- You do not need one on every claim. On a small, clean, fully paid loss, a public adjuster's fee buys you nothing.
Three Adjusters, and Who Pays Each One
Most people meet the word "adjuster" for the first time a few days after a loss, when someone calls to schedule an inspection. It is worth knowing which of three roles that person holds, because they are not variations on a theme. They are paid by different people.
A staff adjuster is an employee of your insurance company. Salary, benefits, performance review, the whole arrangement. When a large national carrier handles an ordinary claim in a market where it has people on the ground, this is usually who comes out.
An independent adjuster is a contractor the insurer hires, typically when its own staff are overwhelmed — after a hailstorm or a hurricane — or when the loss is somewhere it has no staff. They carry their own license and work for several carriers at once.
A public adjuster is the only one of the three a policyholder hires. The fee comes out of the claim rather than out of the insurer's budget, and the work is done for the policyholder.
That is the whole map. Everything below is the detail that matters when you are deciding what to do about the person standing on your roof.
What the Statutes Actually Say
This is the part that settles the argument, and it is worth reading in the law's own words rather than anyone's summary of it. Four of the five states we work in define a public adjuster, and all four define the role by who the adjuster acts for.
Minnesota defines both sides in the same section, which makes the contrast unusually clear. Minn. Stat. § 72B.02 subd. 6 defines a public adjuster as a person who acts "for compensation or any other thing of value on behalf of the insured." Two subdivisions earlier, subd. 5 defines an independent adjuster as a person who "contracts for compensation with insurers or self-insurers."
That is the same statute, drawing the line by who is paying and who is being represented.
Wisconsin draws it even more sharply. Wis. Stat. § 629.01(1) defines an "adjusting service" as an act "on behalf of an insured, in exchange for compensation," and § 629.01(5) defines a public adjuster as someone who performs those services. Then § 629.01(5)(f) carves out, from the definition entirely, "an individual who represents an insurer in negotiations for the settlement of a claim against the insurer."
In Wisconsin, representing the insurer does not make you a different kind of public adjuster. It makes you not a public adjuster.
Florida, at Fla. Stat. § 626.854(1), defines a public adjuster as a person who "acts on behalf of, or aids an insured or third-party claimant in negotiating for or effecting the settlement of a claim or claims for loss or damage covered by an insurance contract."
North Dakota, in chapter 26.1-26.8 of the Century Code, uses "acts for or aids an insured in negotiating for or effecting the settlement of a first-party claim."
South Dakota has no public adjuster licensing chapter at all, which is a fact about the statute book rather than about the work.
Read the four together and the pattern is not subtle. Every state that defines the role defines it by the person the adjuster is acting for.
Why "Independent" Is the Most Misread Word in a Claim
Most homeowners hear "independent adjuster" and reasonably assume it means neutral — a referee rather than a player. The statutory definition above says otherwise. Independence there is a tax and employment concept: the adjuster is a contractor rather than an employee, which is a description of the paperwork between them and the insurer, not of where their judgment sits.
None of that makes an independent adjuster dishonest, and it is worth saying plainly that many are careful and fair. But the structure is what it is. The engagement comes from the carrier, the invoice goes to the carrier, and the next engagement depends on the carrier.
What the Carrier's Adjuster Still Owes You
None of this means the insurer's adjuster is unaccountable. Being paid by the carrier does not put them outside the rules, and the rules are enforceable through the state insurance department rather than through argument.
Two of those duties change how the comparison plays out in practice.
The first is that a reduction or denial has to be explained in the policy's own words. Minnesota is the most explicit: under Minn. Stat. § 72A.201 subd. 4(11), an insurer may not deny a claim on the grounds of a policy provision, condition or exclusion "unless reference to the provision, condition, or exclusion is included in the denial," in writing, with a copy in the claim file.
South Dakota reaches the same place through SDCL § 58-33-67(3), which covers the compromise offer as well as the flat denial. So when an adjuster tells you something is not covered, the provision behind it is a document you are entitled to, not a favor.
The second is that the insurer's adjuster is supposed to tell you about coverage you have not asked about. Minn. Stat. § 72A.201 subd. 4(5) makes it an unfair settlement practice to fail to notify a claimant of the available benefits or coverages they may be eligible to receive. If nothing was ever said about ordinance or law coverage, additional living expense, or debris removal on a loss where they plainly applied, that silence is the thing to raise.
On top of those, every one of our five states puts the insurer on some kind of clock, and they differ enough to be worth knowing separately. We set all five out side by side, with the statutes, in the ice dam guide.
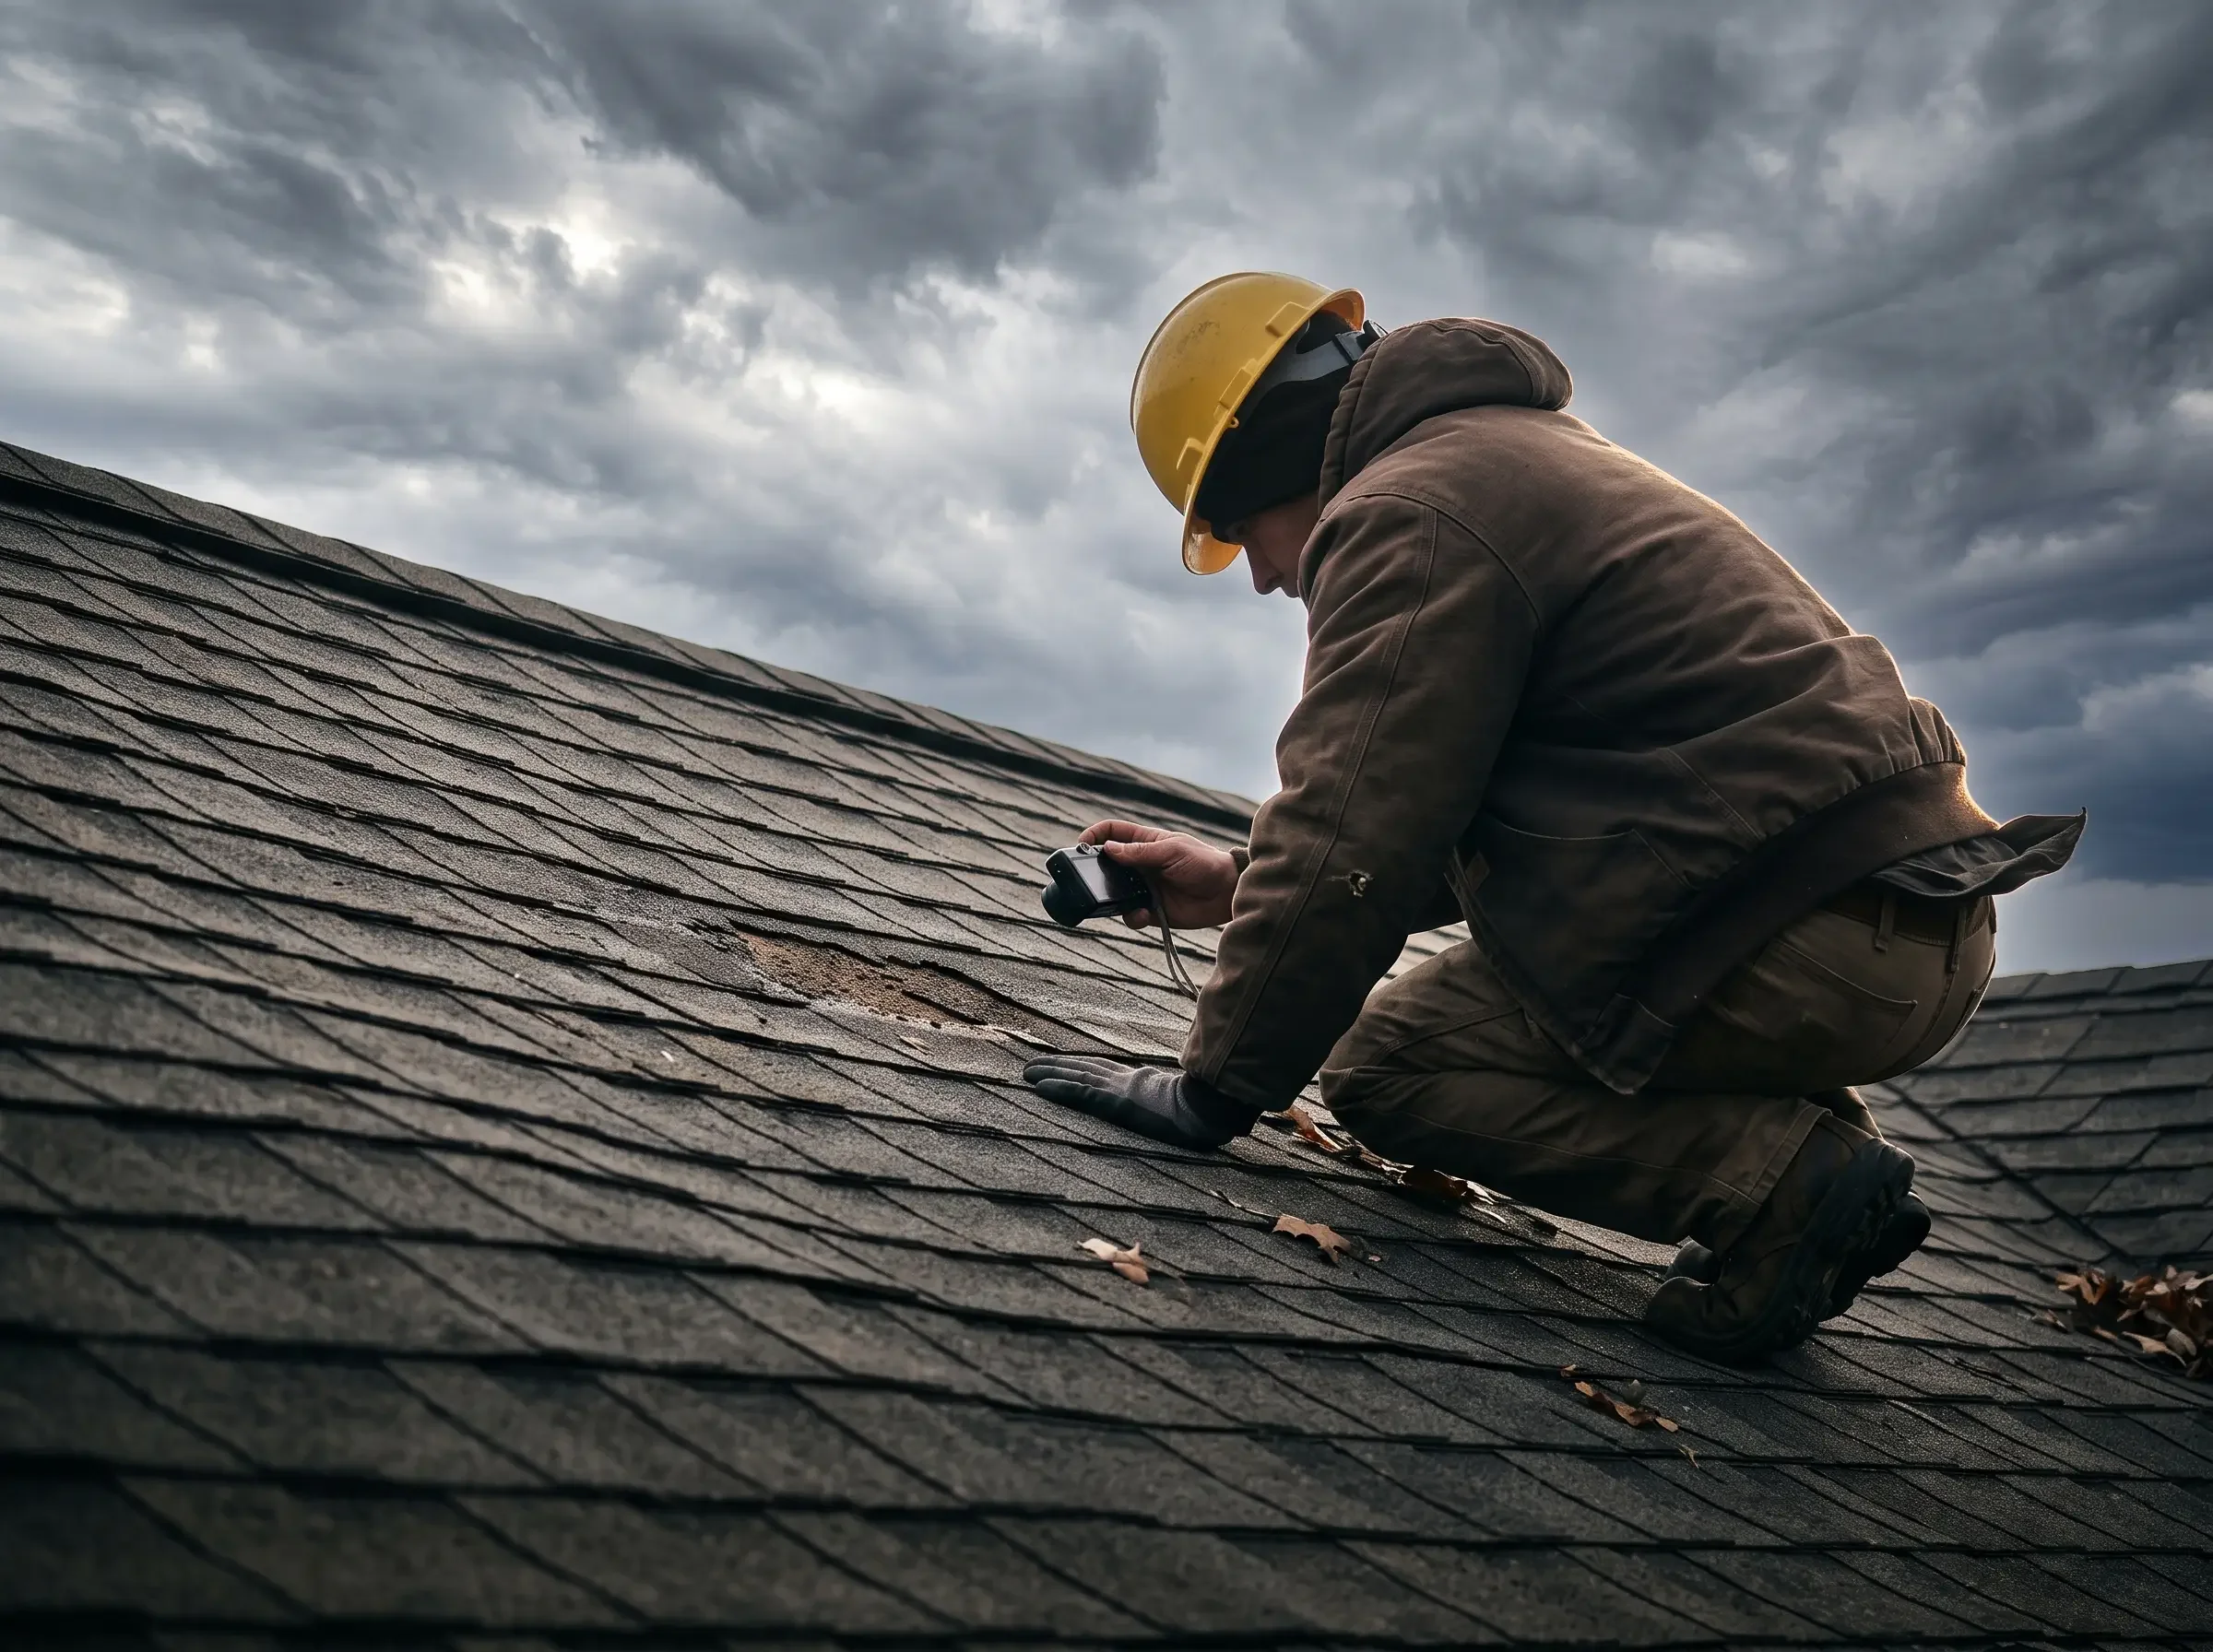
The Same Roof, Two Estimates
When people ask what a public adjuster actually changes, the honest answer is not that we argue harder. It is that the two estimates are built from different starting questions.
The carrier's adjuster is answering: what does this loss cost to repair, under this policy, as I have scoped it? That is a legitimate question and often produces a reasonable number.
A public adjuster is answering a different one: what is the full extent of the damage, what does the policy actually owe on it, and what has not been scoped yet? That turns up the things that are genuinely easy to miss on a first inspection — matching, code upgrades required by the repair, overhead and profit on a multi-trade job, contents, and additional living expense.
Neither question is dishonest. They just do not produce the same estimate, and only one of them is being asked on your behalf.
From Our Files
A commercial property owner came to us on a storm-damaged roof. By his account, his roofer had recommended replacing the whole thing and the carrier's adjuster had pushed back on that recommendation.
We are careful about how we tell this one. The carrier's position here is the client's description of it, recorded at intake, not a document we hold. What the file does record is the shape: a disagreement about repair versus replacement on a commercial roof, and a payment that followed after the claim was worked.
The lesson is the one this whole post is about. Two people looked at the same roof and reached different conclusions, and the difference between them was not expertise. It was which question each of them had been hired to answer.
When You Do Not Need a Public Adjuster
This matters more than the sales case, and most comparison articles skip it.
If your loss is small, the cause is not in dispute, the estimate matches the repair bid you already have in hand, and the check has arrived, you do not need a public adjuster. A fee on a claim that was going to be paid correctly anyway is money you have simply given away.
The same is true if the whole loss sits below or close to your deductible. Run that arithmetic first.
When It Is Worth a Second Look
- The claim has been denied, or reduced with a reason you cannot tie to a specific policy provision.
- The number on the estimate and the number from your own contractor are far apart, and nobody can tell you why.
- The loss is complex or multi-trade — structural damage, smoke, a commercial building, a condo or HOA where unit and association coverage overlap.
- The scope keeps growing as things are opened up and dried out.
- The file has gone quiet past the deadlines above.
- You are being asked to sign or accept something you do not understand, under time pressure.
How to Check Anyone Who Shows Up
- Ask who is paying them. It is a fair question and the answer is short. Staff adjusters and independent adjusters are both paid by your insurer.
- Ask for the license or registration number. Ours are listed at the bottom of this page.
- Read the contract before you sign it, including the cancellation terms. Minnesota gives you 72 hours to cancel a public adjuster contract after signing, under Minn. Stat. § 72B.135 subd. 1.
- Get the fee in writing, as a percentage of what, and of which payments. What a public adjuster costs and what caps it varies by state, and on a supplemental claim the base matters more than the rate.
- Never let anyone tell you not to consult an attorney or an adjuster. In Minnesota that advice is itself a listed unfair practice, under Minn. Stat. § 72A.201 subd. 4(7).
Frequently asked questions
What is the difference between a public adjuster and an insurance adjuster?
Who they act for, and it is written into the statutes rather than left to marketing. Minn. Stat. § 72B.02 subd. 6 defines a public adjuster as someone acting "on behalf of the insured," while subd. 5 defines an independent adjuster as someone who "contracts for compensation with insurers or self-insurers." Florida and North Dakota use the same on-behalf-of-the-insured formula, and Wis. Stat. § 629.01(5)(f) expressly excludes anyone who represents an insurer from being a public adjuster at all.
Is an independent adjuster actually independent?
Independent describes the employment arrangement, not the loyalty. Under Minnesota's definition an independent adjuster is a contractor rather than an employee of the insurer, which is a statement about tax and contracting status. The engagement, the invoice and the next engagement all come from the carrier. That does not make any individual adjuster unfair, but it does mean nobody in that arrangement is working for you.
Does the insurance company's adjuster have any duty to me?
Yes, and it is enforceable through your state insurance department. Minnesota sets deadlines in business days and requires any denial to name the exact provision behind it, under Minn. Stat. § 72A.201 subd. 4 and 4(11). The other four states each impose their own version, and the one in your state is worth knowing before you need it.
Can I hire a public adjuster after the insurance adjuster has already inspected?
Yes, within your deadlines. Nothing in the licensing statutes ties your right to representation to the stage of the claim. What does bind you are the deadlines in your own policy, the notice limits some states set by statute, and your state's suit-limitation period, so the practical answer is that later is allowed but earlier is easier — scope is much simpler to prove before repairs are made and wet materials are thrown out.
Do I always need a public adjuster?
No, and anyone who tells you otherwise is selling. On a small loss with an undisputed cause and an estimate that already matches your repair bid, a contingency fee buys you nothing. The case for representation is a denial, a gap between the offer and the real repair cost, a complex or multi-trade loss, or a file that has stalled.
What does a public adjuster cost compared with the insurance company's adjuster?
The insurer's adjuster is paid by the insurer, not by you — which is also the point. Shoreline's fee is a percentage of the claim payments you receive, with no upfront fee, unless state law sets a different basis for a claim: in Wisconsin, if the insurer pays or commits in writing to pay the policy limit within 5 business days after the loss is reported, a public adjuster may charge only a reasonable hourly rate (Wis. Stat. § 629.05(3)). Several states cap that percentage. The comparison that matters is not the fee against zero, but the likely outcome with representation against the outcome without it.
Are public adjusters licensed in every state?
Not every state licenses them in the same way. Minnesota, Florida and North Dakota each have a licensing framework with a statutory definition. Wisconsin's statute calls it registration: a public adjuster who lives outside Wisconsin must register before adjusting there, and one who lives in Wisconsin may (Wis. Stat. § 629.02(2)). South Dakota has no public adjuster chapter. Where a state licenses or registers public adjusters, you can check that state's insurance department list before you sign anything.
What should I ask the adjuster who comes to my property?
Start with who is paying them, then ask for their license or registration number and which company engaged them. Ask what they scoped and what they did not, and ask for the estimate in writing rather than a verbal summary. If anything is denied or reduced, ask in writing for the specific policy provision behind it — in Minnesota the insurer is required to give you that.
Related Reading
- The fee page above covers what a public adjuster costs, what it is charged on, and the statutory caps by state.
- What do public adjusters do? — the day-to-day of the work, start to finish.
- A denied claim versus an underpaid one — two different problems that need two different arguments.
- The appraisal clause — what happens when the two estimates simply will not meet.
Get a Second Read on the Estimate
If an adjuster has been out and the number does not match what your contractor says the repair costs, the useful next step is a second read of the estimate rather than an argument on the phone.
Send us the estimate and any denial or reduction letter. We will read it and tell you plainly whether the claim needs representation, including when the answer is that it does not. There is no upfront fee for a claim review. If you would rather start with the arithmetic, our coverage gap calculator sizes the distance between an offer and a repair cost.
We handle residential claims and commercial claims, and we are licensed in Minnesota, Wisconsin, Florida, North Dakota and South Dakota.
Sources
- Minn. Stat. § 72B.02 — definitions, subd. 5 and subd. 6 (verified 2026-09-27)
- Minn. Stat. § 72A.201 — claim-handling standards, subd. 4 (verified 2026-09-27)
- Minn. Stat. § 72B.135 — public adjusters, subd. 1 (verified 2026-09-27)
- Wis. Stat. § 629.01 — definitions, (1) and (5)(f) (verified 2026-09-27)
- Wis. Stat. § 629.02 — registration, (1) and (2) (verified 2026-10-23)
- Wis. Stat. § 629.05 — compensation, (3) (verified 2026-10-23)
- Wis. Stat. § 628.46 — timely payment of claims (verified 2026-09-27)
- Fla. Stat. § 626.854 — "Public adjuster" defined (verified 2026-09-27)
- Fla. Stat. § 627.70131 — insurer's duty to acknowledge and act (verified 2026-09-27)
- N.D. Cent. Code ch. 26.1-26.8 — public adjusters, definitions (verified 2026-09-27)
- SDCL § 58-33-67 — unfair or deceptive practices (verified 2026-09-27)
Shoreline Public Adjusters, LLC is licensed in Minnesota (MN 40962416), Wisconsin (WI 21156868), Florida (FL G199012), North Dakota (ND 3004392416), and South Dakota.
Shoreline Public Adjusters, LLC
780 Fifth Avenue South
Suite #200
Naples, FL 34102
Email: hello@teamshoreline.com
Phone: 954-546-1899
Fax: 239-778-9889