
Public Adjuster Pensacola, FL
Wind, Surge and Flood Claims Across Escambia County
✓ No Fee Unless We Recover
✓ Licensed Florida Public Adjusters (#G199012)
✓ Serving The Entire State of Florida
Fill Out the Form Below to Get Started With your Free Claim Review:
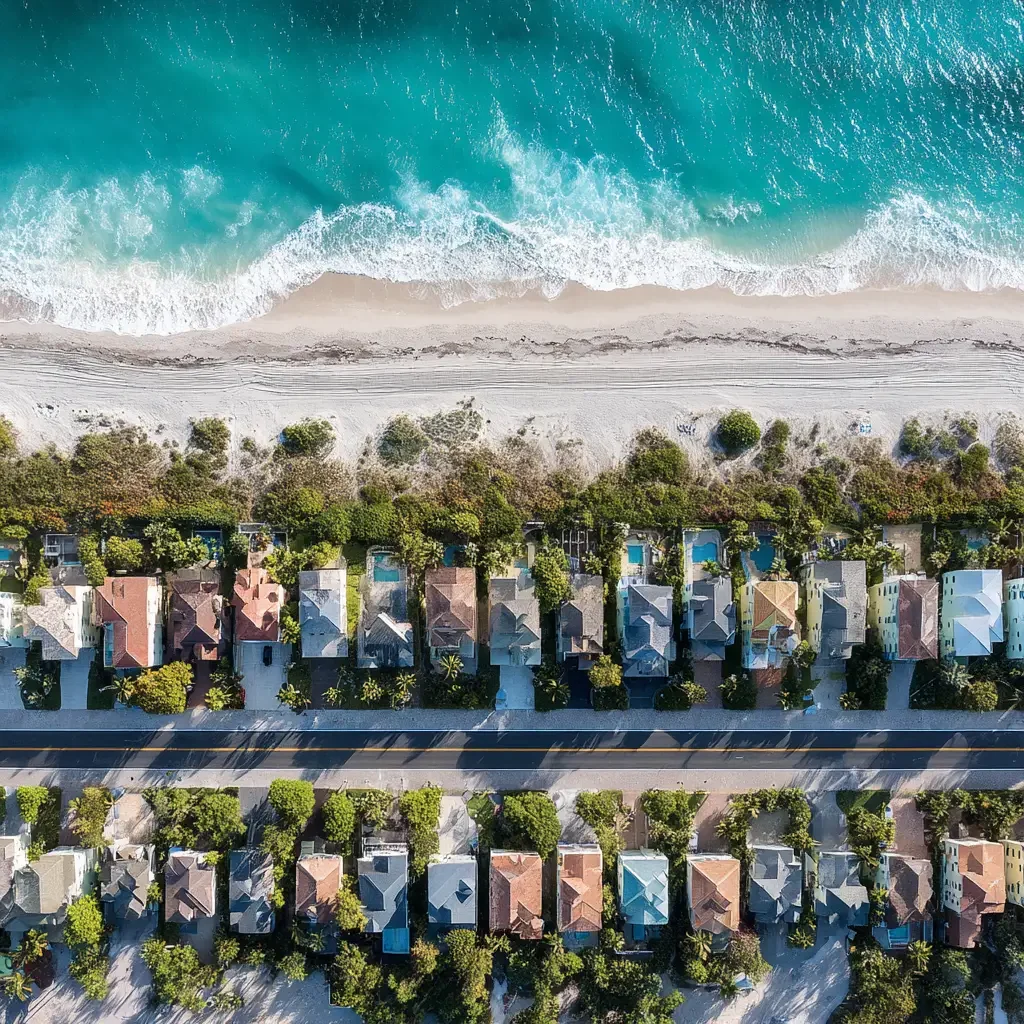
NOAA's entry for downtown Pensacola on September 15, 2020 records near 2 feet of rain arriving together with a near 6 foot storm surge. Two causes, one building, one argument: wind coverage pays for one and a flood policy pays for the other. After Sally, 7,305 Escambia County households held wind coverage and no flood policy at all.

As Seen On:
Get Help With Your Pensacola Insurance Claim

In Escambia County the Argument Is Which Water Did It
Pensacola does not get a clean peril. Hurricane Sally put 20 to 30 inches of rain on the south of the county and pushed a near 6 foot surge into downtown at the same time, and NOAA logged thousands of water rescues across Escambia. Further inland, over central Escambia County, the Perdido River near Barrineau Park crested at 22.30 feet, the fourth highest crest on record. Rain falling through a wind-made opening and surge rising through a doorway look identical a week later, and they are paid by different policies.
That is why the insurance question here is an allocation question. Sally drew 25,414 federal assistance registrations from this county. 8,792 of them reported homeowners coverage; 1,825 reported flood. 7,305 of them had wind coverage and no flood policy, which means that for those owners the split between rain and surge was not a matter of percentages — it decided whether anything was covered at all.
The county's flood record is long enough to make the point on its own. FEMA holds 16,499 Escambia County flood claims across the program's history, and 4,676 of them closed with no building payment. 707 closed under code 06, which FEMA's own dictionary defines as not actual flood. That is a finding about where the water came from, and a finding can be answered with evidence.
Start Your Florida Claim Consultation
We are extremely proud to serve the following states:
We are based in Naples, FL but are licensed and our team services the entire states of Florida, Minnesota, Wisconsin, North Dakota & South Dakota - contact us today to get started!
Escambia County in the Federal Record
One ZIP code area, 32502, lies entirely inside Pensacola in the Census Bureau's 2020 file, so its figures describe the city itself rather than the county around it.
11,823 paid on the building; 4,676 closed with no building payment; 707 under code 06, not actual flood.FEMA NFIP
8,792 of the county's 25,414 Sally registrations reported homeowners coverage; only 1,825 reported flood.FEMA IHP
More than any storm since — 2,452 for Sally in 2020 and 2,401 for Opal in 1995.FEMA NFIP
24 of the county's 40 federal declarations are typed as a hurricane. Sally's is one of the five that carried it.FEMA declarations
Three Florida Rules That Decide Whether You Have a Claim at All
The statewide machinery, meaning reporting windows, insurer response duties and what we may charge, lives on our Florida page. The three below are different: each is a condition the insurer had to satisfy before it can rely on the position it is taking.
Windstorm coverage is required, and a waiver takes your handwriting627.712
An arbitration clause binds you only if all five conditions were met627.70154
The mitigation discounts have to be put in front of you every year627.711
The statewide rules: reporting windows, insurer duties and fee limits
Where We Work in Escambia County, From Perdido Key to Century
Every dated entry below is from NOAA's Escambia County storm record, and every claim figure is filtered to Escambia County rather than taken from a ZIP code total.
Warrington, Perdido Key and the Southwest
The county's heaviest flood exposureZIP code area 32507 carries 5,663 Escambia County flood claims on its own, 1,953 of which closed with no building payment and 286 under code 06 — more than a third of the county's whole file in one stretch of coast. The same area took an EF-1 tornado on the morning of May 10, 2025: it began near Selma Street, crossed Gulf Beach Highway, and near Graupera Street and Rentz Avenue the uplift of a porch awning led to roof damage on one home, with windows broken at another.
Downtown Pensacola and Ferry Pass
Where the rain and the surge metDowntown is the one place a claim figure can describe exactly: 32502 lies entirely inside the city, and FEMA counts 500 flood claims there, 162 closed with no building payment and 30 under code 06, with 150 tied to Ivan and 79 to Sally. The May 13, 2024 flash flood closed L and Garden, Marcus and Texar, Airport and Cobble View, 9th and College, Garden and Devillers, and D and Cervantes. North of there, a compact EF-1 crossed Ferry Pass on February 11, 2025 from Bill Metzger Lane to Copter Road and damaged mostly metal roofing.
Pensacola Beach and the Island
Wind first, water secondA waterspout came onshore just east of the Pensacola Beach pier on May 10, 2025. NOAA rated it EF-1 and put its strongest winds at 90 to 100 miles an hour by the volleyball nets off the Casino Beach Boardwalk, where it tore roofing from a mini golf building and dropped it in a hotel parking lot, knocked down a restaurant sign and threw a barbecue smoker 20 to 30 yards. Island claims turn on the order of events, because wind damage and surge damage reach the same wall from opposite directions.
Cantonment, Molino and North Escambia
Trees, mobile homes and river floodingCantonment accounted for 1,640 Sally registrations and Molino 280, with Century at 234 and Walnut Hill 33. The April 10, 2024 EF-1 began on Pine Forest Road and uprooted numerous very large live oaks: one fell on a home and caused significant damage, and three mobile homes were crushed by uprooted trees along Cycle Drive before the tornado passed over Pine Forest High School. Walnut Hill lost roads to flash flooding on April 6, 2025, one of them partially collapsed.
Nearby pages we serve
Who Is Worth Bringing Into an Escambia County Claim
When rain and surge arrive in the same hour, the file is won or lost on documentation: what the water touched, in what order, and through which opening.
Public Adjuster
Separates the wind loss from the water loss- Documents what the wind opened and what the water reached, then prices each under the coverage that actually pays it.
- Checks the policy paperwork the statutes require — the windstorm waiver, the arbitration endorsement, the mitigation notice — before accepting a coverage position.
- Nothing is owed upfront, and the percentage sits in the agreement you sign, within the statutory caps, before anyone walks the property.
Attorney
Once the dispute leaves the evidence- Necessary when the disagreement is about what the policy means, or about how the insurer has behaved.
- Brings its own calendar and its own costs to a question that is usually settled by documentation rather than argument.
Filing Alone
Free, and unexamined- The carrier's own allocation between wind and water stands unchallenged, and 4,676 Escambia flood claims have closed with no building payment.
- The policy conditions in this section go unchecked, and the reporting window closes on schedule regardless.
The Escambia County Losses We Handle
Nothing below is generic: each card rests on a dated Escambia County entry in NOAA's storm record or on this county's own FEMA claim file.
Windstorm and hurricane
24 of the county's 40 federal declarations are typed as a hurricane. Fla. Stat. 627.712 requires that a residential policy provide windstorm coverage at all, and a carrier saying otherwise should be able to produce a waiver in your own handwriting. Our hurricane claims page covers the coverage itself.
Storm surge and rising water
Surge comes from outside and rises, which puts it on a flood policy, and 7,305 Escambia households who registered after Sally had no flood policy to put it on. Our water and flood claims page takes the three water coverages apart.
Tornado and tree impact
Five tornadoes sit in the county's recent NOAA record, and the April 2024 EF-1 did its damage through trees: very large live oaks uprooted, one onto a house, three mobile homes crushed along Cycle Drive. A tree through a roof splits across the dwelling, debris removal and sometimes other structures, each with a sublimit of its own. See our wind and tornado claims page.
Roofs, metal roofing and openings
The February 2025 Ferry Pass tornado damaged mostly metal roofing, and the Warrington tornado began with a porch awning lifting before the roof failed. Rain that got in afterwards belongs to the wind coverage, but only if the sequence can be shown, which is why images taken before anything is tarped or dried matter more than any estimate.
Flash flooding away from the coast
NOAA logs five flash floods in the county's recent entries, from six named Pensacola intersections on May 13, 2024 to a partially collapsed road at Walnut Hill in April 2025. Inland flash flooding is not surge, and it is not always a flood-policy loss either — where the water came from decides it.
Mobile and manufactured homes
The statutory windstorm waiver in Fla. Stat. 627.712 names mobile homes in its own wording, and the April 2024 tornado crushed three of them along Cycle Drive, north of the city. Tie-downs, replacement cost and the separate limits that apply to a manufactured home all change what a correct estimate looks like.
How We Build an Escambia County File
Establish which water did the damage, then check whether the policy's own paperwork supports the coverage position the carrier has taken.
Fix the order of events
NOAA gives the date, the event type and often the street. Rain through a wind-created opening, surge from outside, and inland flash flooding are three different claims, and the documentation that separates them is photographic and elevational, not argumentative.
Read the paperwork the statutes require
If the carrier says there is no windstorm coverage, Fla. Stat. 627.712 says a waiver in your handwriting exists, signed by every named insured and approved by your mortgageholder. If it points at an arbitration clause, Fla. Stat. 627.70154 sets five conditions. We ask for those documents first.
Price every coverage part, not just the structure
4,676 Escambia County flood claims closed with no building payment. That is not the same as paying nothing: contents, other structures, debris removal and loss of use each carry limits of their own, and on a tree-fall or surge loss they are often where the money actually sits.
Diary the deadlines on day one
Reporting limits start at the date of loss, not the date someone tells you about them, and the insurer's own response duties start at notice. Our Florida page lists both. We put each date on the file before anything else happens, because a missed window cannot be argued back.
Everything that applies statewide rather than to Escambia County — what the insurer owes you once notice is given, and what a public adjuster may charge — is gathered on our Florida public adjuster page.
Why Pensacola Owners Bring Us In
Licensed, bonded and regulated
We hold Florida public adjuster license #G199012 from the Florida Department of Financial Services, and the firm is licensed in Minnesota, Wisconsin and North Dakota as well. Every Florida claim we handle is backed by a $50,000 surety bond — the amount Fla. Stat. 626.865, headed Public adjuster's qualifications, bond, requires before anyone may adjust a claim for you in this state.
No upfront fee
There is no upfront fee. Our compensation is a percentage of the recovery, written into the agreement you sign before any inspection takes place and inside the limits Florida law places on public adjuster compensation. The caps, and what they do and do not cover, are set out on our Florida public adjuster page.
We have read this county's loss record
Not a slogan — the figures on this page come from NOAA's Escambia County entries and FEMA's claim file for this county. Sally's rain and surge arriving together downtown, the EF-1s at Pensacola Beach, Warrington and Ferry Pass in 2025, the live oaks on Pine Forest Road in 2024, and the 707 county flood claims closed under FEMA's code 06. Knowing which storm did what, on which date, is how an allocation argument gets won.
One team from first inspection to final payment
Your file is not handed off. The same team runs the inspection, attends the carrier walk-throughs, answers the document requests and takes your calls, so nobody has to be brought up to speed halfway through. That matters particularly for families attached to NAS Pensacola, where orders can arrive mid-claim: the file keeps moving whether or not you are still in the county.
Recognized outside our own website
Shoreline Public Adjusters has been featured in Forbes, Investopedia, Realtor.com and other outlets, and the firm holds membership in NAPIA, the National Association of Public Insurance Adjusters, and in FAPIA, the Florida Association of Public Insurance Adjusters.
Pensacola Public Adjuster FAQ: Surge, Windstorm Coverage and Escambia County Claims
Can a Hurricane Sally claim still be reopened?
My insurer says I have no windstorm coverage. Can that be right?
Is storm surge covered by my homeowners policy or my flood policy?
How much does Escambia County actually flood?
My policy has an arbitration clause. Am I stuck with it?
Escambia County got federal Individual Assistance for Sally. Does that change my insurance claim?
Short Payment on an Escambia County Claim? Start With the Policy, Not the Estimate
On a wind-and-water loss the gap usually sits in a coverage position rather than in a line-item price, and three documents decide it.
The windstorm waiver, if the carrier says there is none
Fla. Stat. 627.712 requires that waiver to be in your own handwriting, signed by every named insured and dated, with written mortgageholder approval where the building is financed. Ask for it in writing.
The allocation between wind and water
Read which cause the adjuster assigned each area to. NOAA records near 2 feet of rain and a near 6 foot surge downtown on the same date, so both causes were present and the split is an argument, not a fact.
The non-payment code on a flood closure
707 Escambia County claims closed under code 06, which FEMA defines as not actual flood. That is a finding about origin, and findings can be met with evidence of where the water came from.
Send those three documents plus the declarations page. We will check the coverage position against what NOAA logged in Escambia County that day, and say whether there is a supplement here or not.
Why Sally Claims Are Closed and What Is Not
Hurricane Sally came ashore in September 2020, and that loss ran on the framework in force then: 2 years to give notice and 3 years for a supplemental claim. Both windows shut by September 2023. The current 1-year and 18-month limits in Fla. Stat. 627.70132 arrived with ch. 2022-271 effective December 16, 2022, for policies issued or renewed after that date.
What is open is everything since — the February and May 2025 tornadoes, the May 2024 and April 2025 flash floods, and the ordinary wind and water losses that never make a declaration at all.
Start a Pensacola Claim Review
No upfront fee. Three things get a review moving: when it happened, what the insurer has put in writing, and any images from before the drying and tarping started.