
Public Adjuster Panama City, FL
Tornado, Hurricane and Wind Claims Across Bay County
✓ No Fee Unless We Recover
✓ Licensed Florida Public Adjusters (#G199012)
✓ Serving The Entire State of Florida
Fill Out the Form Below to Get Started With your Free Claim Review:
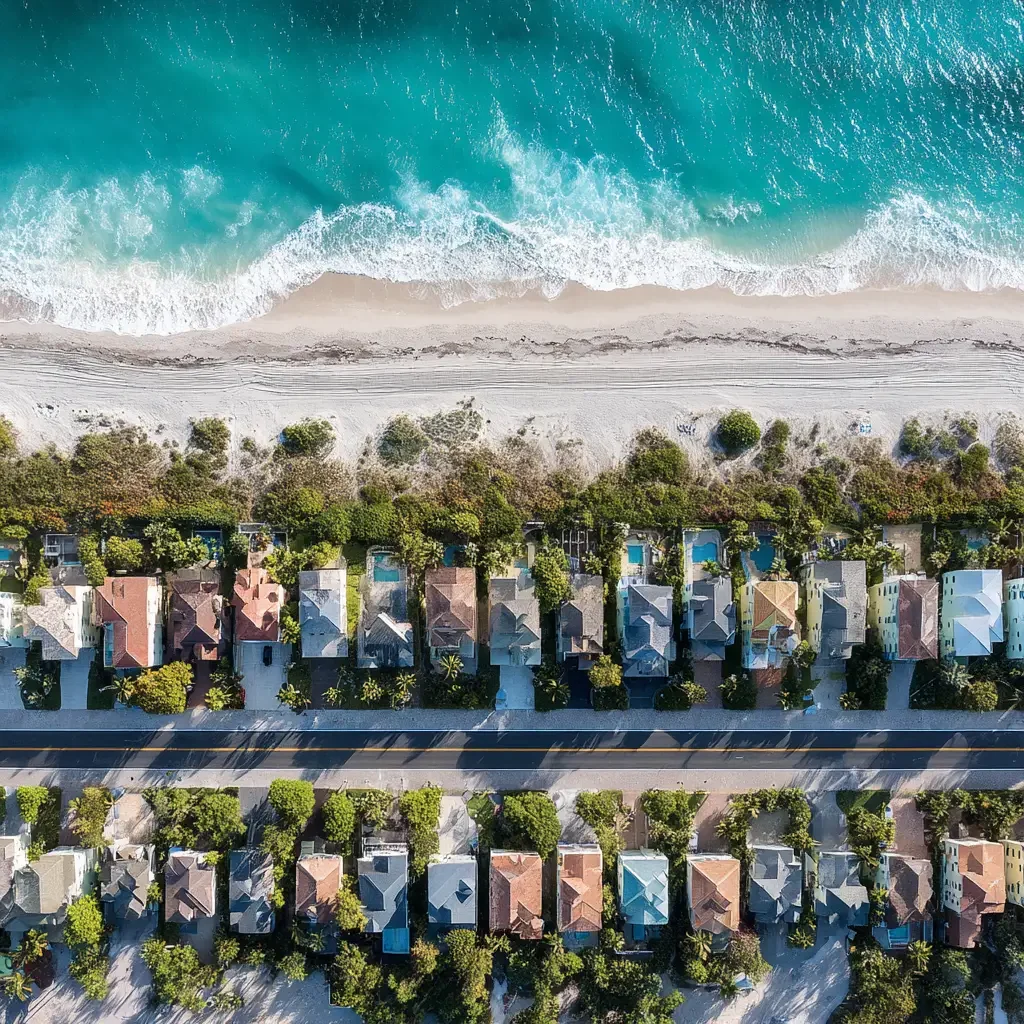
On January 9, 2024 an EF-3 tornado came ashore at Panama City Beach with winds estimated near 140 miles an hour, destroying one beachfront home and heavily damaging two apartment buildings. It was not a hurricane, and in Florida that distinction decides which deductible your carrier may apply. Bay County's costliest recent wind losses arrived in January and October, nowhere near a hurricane window.

As Seen On:
Get Help With Your Panama City Insurance Claim

In Bay County the Fight Is Over Which Storm Did It
Panama City is known for one storm, and Hurricane Michael's notice deadlines ran out years ago. What is claimable here now is wind, and the wind that has cost this county the most recently did not come from the tropics at all. Four tornadoes crossed Bay County on the morning of January 9, 2024, and NOAA's damage figures for two of them alone total $20.35 million. A tornadic waterspout came ashore at Mexico Beach on October 27, 2025.
That matters because of how Fla. Stat. 627.4025 is written. For hurricane-coverage purposes a windstorm means wind, gusts, hail, rain, tornadoes or cyclones caused by or resulting from a hurricane — and the hurricane's duration runs from the first hurricane warning anywhere in Florida until 72 hours after the last watch or warning ends. A January supercell satisfies neither limb. On a policy carrying a 2 percent hurricane deductible, the difference between the right classification and the wrong one is thousands of dollars subtracted before the carrier pays anything.
The water argument runs backwards from what people assume too. FEMA's flood file ties 2,980 Bay County claims to Hurricane Opal in 1995 and only 2,129 to Michael, so the Category 5 was largely a wind event here while a Category 3 thirty years ago was the bigger flood. Of the households that registered for federal help after Michael, 18,704 held a homeowners policy and no flood policy, which means the wind-versus-water finding decided whether they had coverage at all.
Start Your Florida Claim Consultation
We are extremely proud to serve the following states:
We are based in Naples, FL but are licensed and our team services the entire states of Florida, Minnesota, Wisconsin, North Dakota & South Dakota - contact us today to get started!
What the Federal Files Actually Record for Bay County
Counted at the county level on purpose: no ZIP code area lies entirely inside Panama City, so a ZIP-level figure would describe the wrong place.
26 typed as a hurricane, 4 as a flood, and only 5 ever carried Individual Assistance. Sixteen have landed since Michael; 2 carried it.FEMA declarations
40,691 name Panama City itself, with 7,145 from Lynn Haven, 4,333 from Panama City Beach and 1,037 from Mexico Beach.FEMA IHP
Of 25,045 county registrants reporting homeowners, against 7,026 reporting flood. Where the damage came from decided who was covered.FEMA IHP
Out of 9,005 Bay County claims across the program's history, 6,002 of which paid on the building. 606 closed under code 06.FEMA NFIP
Three Things the Deductible Statute Gives You That Carriers Rarely Mention
Florida's statewide deadlines and the hurricane-deductible window are set out on our Florida page. These three provisions decide Bay County files, and they sit in the deductible statute rather than the deadline statutes.
The deductible options, and a notice at every renewal627.701
The deductible is annual, not per storm627.701
Losses under the deductible can be banked toward the next one627.701
Florida's claim deadlines, the pay-or-deny clock and the fee caps
Bay County Areas We Work, From Lower Grand Lagoon to Mexico Beach
Every dated entry below comes from NOAA's Bay County storm records, and the county assignments come from the Census Bureau's place-by-county file.
Panama City Beach and Lower Grand Lagoon
Where the EF-3 came ashoreThe January 9, 2024 tornado moved onshore along Spyglass Drive and tracked northeast across and along Thomas Drive, heavily damaging two apartment buildings and causing significant structural failure at a large boat storage facility. A satellite vortex of the same parent tornado made landfall at the western edge of St. Andrews State Park. This side of the bay also carries most of the county's flood history: 1,637 claims in the 32407 area and 1,058 in 32413.
Lynn Haven and North Bay
Roofs, manufactured homes and the lake shoreThe second January 2024 tornado was rated EF-2 here, removing large sections of a roof on Joanna Lane and destroying a double-wide manufactured home in the Resota Beach area on the west shore of Deer Point Lake, with $5 million recorded. Lynn Haven alone accounted for 7,145 of the county's Michael assistance registrations, and a manufactured-home loss raises tie-down and replacement-cost questions that a site-built roof claim never does.
Callaway, Parker and the East Side
Where the tornado tracks run inlandA third EF-2 touched down near South Tyndall Parkway and North Lakewood Drive at an estimated 115 miles an hour, heavily damaging two roofs and removing another along Chipewa Street before dissipating near Cherry Street. Further east, a waterspout came ashore at Mexico Beach at 6:30 am on October 27, 2025 and threw a beachfront hotel roof across U.S. 98 into an RV park. Mexico Beach is in Bay County; Apalachicola, often grouped with it, is in Franklin County.
Nearby pages we serve
Who Should Take a Bay County Claim Forward
A Bay County wind file usually turns on one thing: which storm the carrier assigns the damage to, because the answer sets the deductible it subtracts before paying anything.
Public Adjuster
Dates the loss and tests the deductible- Documents the scope, prices the repair, and dates the loss to a specific NOAA-verified event with its own rating and street.
- Tests whether a hurricane deductible can lawfully reach the loss at all before accepting the arithmetic on the estimate.
- No upfront fee; the contingency percentage is set out in the signed agreement, inside the statutory caps, before any inspection happens.
Attorney
For coverage language and bad faith- Necessary once the dispute turns on policy wording, bad faith conduct or a signed release.
- Adds litigation deadlines and discovery to what is often a scope argument, and is rarely the right first call on a $30,000 roof.
Filing Alone
No fee, and no challenge- The carrier's classification of the storm, and the deductible that follows from it, goes unchallenged.
- No Xactimate scope to argue from, and the notice bars in Fla. Stat. 627.70132 run whether or not you know them.
The Bay County Losses We Handle
Each entry below traces to a dated NOAA record for this county or to FEMA's Bay County claim file.
Tornado and straight-line wind
Nine tornadoes sit in NOAA's recent Bay County record, including the EF-3 at Panama City Beach and two EF-2s on the same January morning. A tornado not caused by or resulting from a hurricane is not a hurricane loss under Fla. Stat. 627.4025, so the hurricane deductible has no application to it. Our wind and tornado claims page covers the coverage itself.
Hurricane and tropical storm
26 of this county's 49 federal declarations are typed as a hurricane. Where a loss does fall inside a hurricane window the deductible is annual rather than per storm, and 2 percent of a dwelling limit puts real money on getting that arithmetic right. See our hurricane claims page.
Flash flood and rising water
NOAA records 14 flash floods in the county's recent entries, including 3 to 4 inches of rain in one hour on August 13, 2018 that put roads under water estimated up to 2.5 feet and flooded classrooms at Haney Technical Center. Rising water is a flood policy question; wind-driven rain through a wind-created opening is not.
Roof openings and interior water
The Oasis Worship Center lost part of its metal roof to 65-knot winds on Front Beach Road on March 31, 2025. Interior water that entered through a wind-created opening is claimed under the wind coverage, and the documentation proving the opening came first is what carries it.
Other structures and manufactured homes
The January 2024 EF-2 destroyed one double-wide manufactured home near Deer Point Lake and significantly damaged another. Manufactured homes, boat storage, docks, pool cages and fencing sit under different coverage parts and limits than the dwelling, and they are routinely missing from a first estimate.
How a Bay County File Gets Built
Name the storm, then test whether the carrier's deductible can lawfully apply to it.
Date the loss to a verified event
NOAA's Bay County record gives an event type, a date, a rating and often a street. A claim dated to the January 9, 2024 EF-3 or the October 27, 2025 Mexico Beach EF-1 is a different claim from one dated to a hurricane, and that record is public.
Test the hurricane deductible
Two questions settle it under Fla. Stat. 627.4025: was the wind caused by or resulting from a hurricane, and did the loss fall between the first Florida hurricane warning and 72 hours after the last watch or warning ended. If either answer is no, that deductible does not belong on the estimate.
Separate wind from rising water
606 Bay County flood claims closed under code 06, not actual flood. Rain driven through an opening the wind created is a wind claim; water that rose from outside is a flood claim. Different policies pay them, and for 18,704 county households after Michael only one of the two existed.
Hold the statutory clock
The notice bars and the insurer's pay-or-deny obligation are set out in full on our Florida page, and they run whether or not anyone reminds you. Every date goes on the file the day we take it.
Florida's statewide rules — the notice bars, the acknowledgment and inspection deadlines, the hurricane-deductible window and the public adjuster fee caps — are set out on our Florida public adjuster page. To see what a percentage deductible actually costs against your own dwelling limit, our Florida hurricane deductible calculator does the arithmetic.
Panama City Public Adjuster FAQ: Tornadoes, Deductibles and Bay County Claims
A tornado damaged my Panama City home. Can the insurer apply my hurricane deductible?
Is the hurricane deductible charged once a year or once per storm in Florida?
Can I still do anything about a Hurricane Michael claim?
How much flood risk does Bay County actually carry?
Does a federal disaster declaration mean help is coming to Panama City?
How does the fee work?
Paid Less Than the Repair Costs? Check These Three Lines
Three lines on the paperwork are where a short payment usually hides: the deductible, the renewal notice, and the coverage part each item was priced under.
The deductible line on the estimate
Check which deductible the carrier subtracted and which storm it named. If the damage came from the January 9, 2024 tornadoes or the October 27, 2025 Mexico Beach waterspout, no hurricane was involved and Fla. Stat. 627.4025 does not reach it.
The renewal notice you were owed
Fla. Stat. 627.701 requires notice of the available hurricane deductible amounts with every renewal and says failure to provide it violates the insurance code. Pull your last two renewal packets and look for it.
The coverage part each item was paid under
Manufactured homes, boat storage, docks, pool enclosures and fencing carry their own limits. The January 2024 tornado damaged every one of those categories in this county, and an estimate that priced only the dwelling is an incomplete estimate.
Forward those three documents and we will read them against NOAA's record for the date you give us, then say plainly whether a supplement is worth filing.
Why a Federal Declaration Does Not Repair Your Roof
Bay County has drawn 16 federal declarations since Hurricane Michael and only 2 of them carried Individual Assistance. Across the county's whole record, 5 of 49 did. A declaration opens public assistance channels and can extend the insurer's pay-or-deny clock; it does not repair a roof.
Your policy does that, and which policy pays turns on which storm the file names.
Start a Panama City Claim Review
No upfront fee. Bring the storm date, the carrier's estimate showing which deductible it applied, and any images of the roof or the interior taken before repairs.