
Public Adjuster Vero Beach, FL
Tornado, Wind and Hurricane Claims in Indian River County
✓ No Fee Unless We Recover
✓ Licensed Florida Public Adjusters (#G199012)
✓ Serving The Entire State of Florida
Fill Out the Form Below to Get Started With your Free Claim Review:
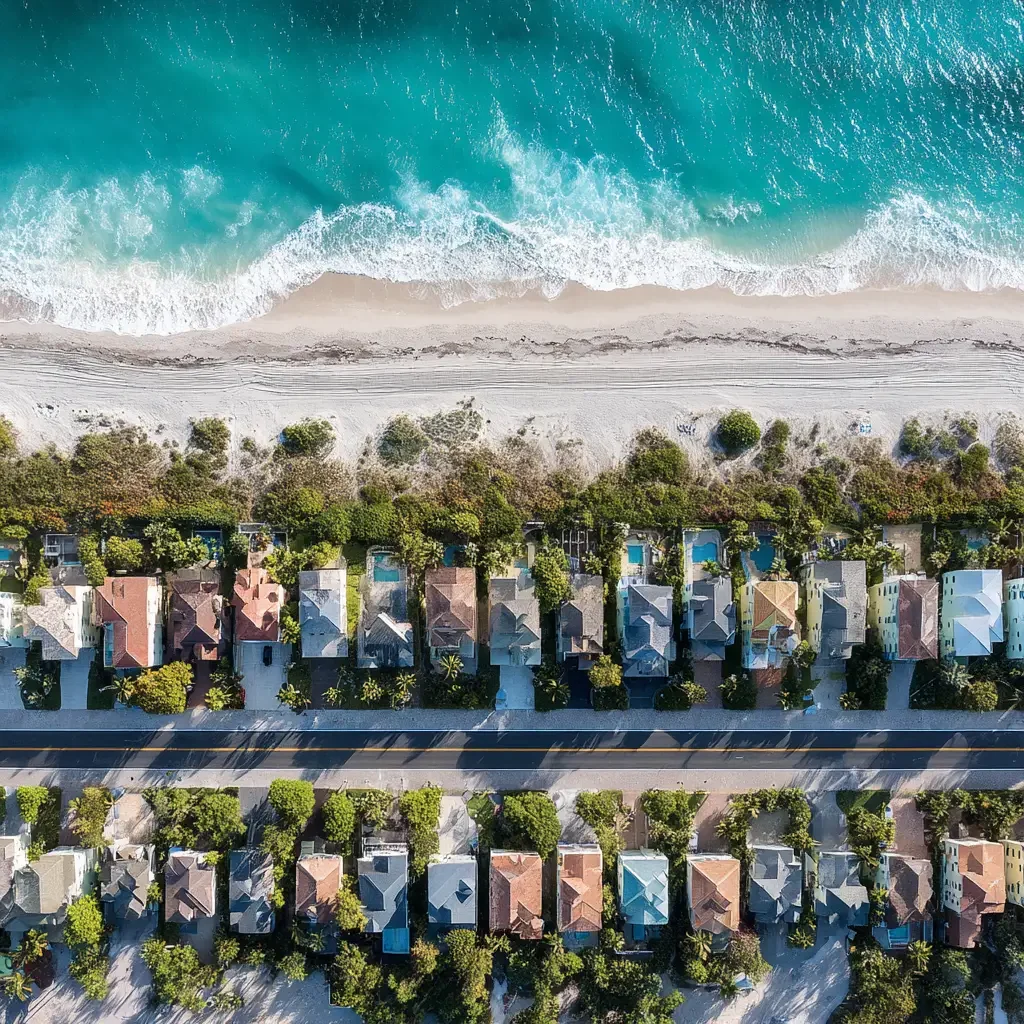
It was Hurricane Milton's rainbands, not its eye, that reached Indian River County. They still produced five rated tornadoes here on the afternoon of October 9, 2024, and NOAA records $59.1 million in property damage from them. Two of the five went through downtown Vero Beach.

As Seen On:
Get Help With Your Vero Beach Insurance Claim

The Storm That Does the Damage Here Is Often Somewhere Else
A hurricane does not have to come ashore on Indian River County to wreck part of it. On October 9, 2024 Milton's rainbands put five rated tornadoes across this county in a single afternoon. The worst, an EF-2 carrying $39 million in recorded damage, arrived already formed from St. Lucie County and tore through Vero Beach Highlands. A supermarket on US-1 lost windows and had roof air-conditioning units torn loose and dropped to the ground. A car was flipped.
Downtown took two of them. The second, an EF-1 with $12 million recorded, ran the railway between 20th Street and the airport with gusts to 100 miles an hour, stripping roofs off several businesses and shifting a large metal warehouse off its foundation as the walls and roof came down near the tracks at 19th Place. The first crossed the police department at about 2:53 pm; a mesonet station there clocked a 92 mile-an-hour gust two minutes later. The same storm dropped 10 to 12 inches of rain on the east of the county and left standing water up to three feet deep.
That is the pattern worth understanding before a carrier assigns your damage to anything. These losses came out of a hurricane, so the hurricane deductible and the hurricane window reach them, and the amount subtracted before anything is paid is not the same as it would be for an ordinary wind claim. The older lesson is the same shape: Frances and Jeanne, three weeks apart in September 2004, still account for 2,168 of the 3,349 flood claims FEMA has on file for this county.
Start Your Florida Claim Consultation
We are extremely proud to serve the following states:
We are based in Naples, FL but are licensed and our team services the entire states of Florida, Minnesota, Wisconsin, North Dakota & South Dakota - contact us today to get started!
What the Record Shows for Indian River County
Counted at county level, because that is the unit both FEMA's claim file and NOAA's storm record use here.
Five rated tornadoes from Milton's rainbands on October 9, 2024: an EF-2 at $39M, EF-1s at $12M and $8M, and two EF-0s.NOAA Storm Events
Almost exactly half of every flood claim FEMA holds for this county. 482 of them closed under code 06, not actual flood.FEMA NFIP
Frances on September 4 and Jeanne on September 25, 2004 — 1,211 and 957 claims, out of 3,349 for the whole county record.FEMA NFIP
22 of the county's 35 federal declarations are typed as a hurricane, and 9 of the 35 activated Individual Assistance.FEMA declarations
Three Documents Your Insurer Owes You, and What Happens If It Does Not Send Them
Florida's reporting windows, the pay-or-deny clock and the public adjuster fee limits all live on our Florida page. The three rules below are different in kind: each one attaches a consequence to a piece of paper, and each consequence runs your way when the paper is missing.
A Homeowner Claims Bill of Rights, within 14 days627.7142
You cannot be dropped while the damage is unrepaired627.4133
A coverage change at renewal has to be announced in 14-point bold627.43141
Where We Work in Indian River County
Every dated entry below comes from NOAA's Indian River County storm record.
Downtown Vero Beach and the Rail Corridor
Where both downtown tornadoes trackedThe EF-1 that did $12 million in recorded damage strengthened along the railway between 20th Street and the Vero Beach airport with gusts to 100 miles an hour, taking roofs off several businesses and shifting a large metal warehouse off its foundation near the tracks at 19th Place. The other crossed the police department at about 2:53 pm after touching down near US-1 at 12th Street. Commercial roof loss and a collapsed warehouse are business interruption questions as much as building ones.
Oslo and Vero Beach Highlands
The EF-2's pathThe county's costliest tornado of the outbreak entered here already formed from St. Lucie County, with $39 million recorded. NOAA describes multiple properties with roof and outbuilding damage and healthy hardwoods toppled or snapped within a few blocks of 6th Avenue SW, and farther north along US-1 a supermarket with broken windows, roof air-conditioning units dislodged and fallen, and a car flipped — damage consistent with EF-1 winds of 90 to 110 miles an hour.
Vero Beach South and Wabasso
Where the water wentMilton's rainbands dropped 2 to 4 inches on the west of the county and as much as 10 to 12 inches in the east, with numerous roads impassable and standing water up to three feet in places. NOAA notes minor water intrusion in a few homes particularly around Vero Beach South, and a daily record 7.71 inches at the Vero Beach airport. Water that entered because a wind-created opening was already there is a wind claim, not a flood one.
Fellsmere, Blue Cypress Lake and the West County
Rural, and still in the outbreakTwo of the five tornadoes stayed west. One produced minor damage to a barn off Fellsmere Road; the other was tracked by radar debris signature west of Blue Cypress Lake with no known property damage. Agricultural buildings, barns, packing houses and equipment sit under coverage parts and limits that a dwelling policy does not touch, which is why a rural loss is often underpriced rather than denied.
Nearby pages we serve
Who Should Handle an Indian River County Claim
A tornado inside a hurricane produces two arguments at once: how much the repair costs, and which deductible applies to it.
Public Adjuster
Documents the scope and tests the deductible- Prices the building, the contents, the other structures and, for a business, the interruption, instead of pricing the roof and stopping.
- Asks for the three documents the statutes above require, because a missing notice changes what the insurer can do next.
- No upfront fee, with the percentage written into the agreement before any inspection and inside Florida's statutory limits.
Attorney
When the dispute stops being about evidence- The right call on policy interpretation, a signed release, or an insurer's conduct.
- Brings deadlines and costs of its own to what is usually a documentation problem first.
Filing Alone
Free, and unchecked- 1,676 of this county's 3,349 flood claims have closed with no building payment, and a closure nobody answers stays closed.
- The notices the insurer owes you go unrequested, and the reporting window closes on schedule either way.
What each of these three can and cannot do under Florida law
Indian River County Losses We Take On
Six losses this county actually had, each traceable to a date in NOAA's Indian River record or a line in FEMA's file for it.
Tornado and straight-line wind
Eight tornadoes sit in NOAA's recent record for this county, five of them in one afternoon. A tornado spawned by a hurricane's rainbands is still a hurricane loss, which changes the deductible rather than the coverage. Our wind and tornado claims page covers the coverage itself.
Hurricane and tropical storm
22 of the county's 35 federal declarations are typed as a hurricane, and Frances and Jeanne in 2004 still account for 2,168 of its 3,349 flood claims. See our hurricane claims page.
Commercial roof loss and business interruption
The downtown EF-1 stripped roofs from several businesses and brought a metal warehouse down near the tracks at 19th Place, and the EF-2 took out a supermarket's windows and rooftop units along US-1. When a building cannot trade, the lost income is a separate coverage with its own proof requirements. Our business interruption page sets those out.
Roofs, rooftop equipment and openings
Dislodged rooftop air-conditioning units, lifted roof decking and broken windows are the signature of this outbreak. Rain that follows the opening belongs to the wind coverage, and the photographs that establish the sequence matter more than the estimate that follows.
Flash flooding and water intrusion
10 to 12 inches of rain in the east of the county, roads impassable, standing water up to three feet, and a daily rainfall record at the airport. Separately, 482 county flood claims closed under code 06, which FEMA's data dictionary defines as not actual flood. Where the water started is an evidentiary question, and photographs and elevations are what answer it.
Agricultural buildings and other structures
Two of the five tornadoes stayed in the rural west, one damaging a barn off Fellsmere Road. Barns, packing houses, groves, equipment, fencing and pole buildings carry limits separate from any dwelling, and an estimate built around the house alone will simply have left them out.
How We Build an Indian River County File
Establish which storm the damage belongs to, then ask the insurer for the paperwork the statutes already require it to produce.
Tie the loss to a dated event
NOAA's county record gives the date, the rating, the gust and often the street. A loss dated to the October 9, 2024 outbreak sits inside a hurricane, which decides the deductible; a loss from an ordinary squall does not.
Request the estimate and the confirmation
Fla. Stat. 627.7142 entitles you to a copy of the carrier's detailed estimate within 7 days of its adjuster producing it, and to written confirmation of the coverage position within 30 days of a complete proof of loss. Both are requests almost nobody makes, and both put the carrier's reasoning on paper where it can be answered.
Price every coverage part, including lost trade
1,676 of 3,349 claims here closed without a building payment — which does not mean they paid out nothing. A policy pays the structure, what was inside it, the detached structures, the debris, somewhere to live, and for a business the trade it lost, each against a separate limit. On a roof-off commercial loss the lost trade is often the biggest line of the lot.
Watch the renewal, not just the claim
Fla. Stat. 627.4133 stops an insurer dropping you until the repair is done or a year after the final payment, and Fla. Stat. 627.43141 makes a coverage change at renewal depend on a notice in 14-point bold. Both become relevant in exactly the months after a claim, which is when people stop paying attention.
The rules that are the same in Orlando as they are here — how long you have to report, how fast the carrier has to move, what we are allowed to bill — sit on our Florida public adjuster page rather than being repeated on every city page.
What We Bring to an Indian River County File
Licensed and bonded in Florida
Firm license #G199012, plus the $50,000 bond that Fla. Stat. 626.865 requires of any public adjuster before they may work a claim for you here. Also licensed in Minnesota, Wisconsin and North Dakota.
No upfront fee
The percentage is in the signed agreement before anyone inspects anything, within Florida's statutory limits — which are listed on our Florida public adjuster page.
This county's own numbers, not generic ones
Everything quoted above is traceable: NOAA's Indian River entries for October 9, 2024 and for September 2004, and FEMA's claim file for Indian River County — down to the 92 mile-an-hour gust logged at the police department and the 482 closures carrying code 06. A deductible argument is won with dates and ratings, which is why we start by looking them up.
Commercial losses as well as homes
This outbreak took roofs off businesses, dropped rooftop units through a supermarket roofline and collapsed a warehouse. Those files turn on business interruption, code-driven repairs and equipment as much as on the building, which is a different exercise from a residential roof claim.
Vero Beach Public Adjuster FAQ: the Milton Tornadoes, Deductibles and Indian River County Claims
Milton never hit Vero Beach. Why was there so much damage?
Is tornado damage from a hurricane treated as a hurricane claim?
Can my insurer drop me after I file a claim here?
What documents is my insurance company actually required to give me?
My claim closed without paying for the building. Is that a denial?
How much of this county's flood history is just 2004?
If the Payment Does Not Cover the Repair, Start With Their Paperwork
On a tornado-inside-a-hurricane loss the shortfall is usually in the scope or the deductible, and both are visible on paper you are entitled to have.
The carrier's own detailed estimate
Fla. Stat. 627.7142 gives you a copy within 7 days of the adjuster generating it. Set its line items beside what the roof, the rooftop units, the interior and, for a business, the downtime actually cost. You cannot argue scope without the carrier's own arithmetic in front of you.
The written coverage position
On written request after a complete proof of loss, the same section entitles you to confirmation within 30 days that the claim is covered in full, partially covered or denied. A position in writing is answerable; a phone call is not.
The deductible line, and which storm it names
The October 9, 2024 tornadoes came out of Milton's rainbands, so a hurricane deductible can reach them. That is worth checking rather than assuming, because the percentage applied and the storm named have to match.
Send those two documents plus your declarations page. We will check them against what NOAA logged in this county on the date you give us, and say plainly whether there is more owed or not.
What a Second Hurricane in One Year Does to the Deductible
This county has lived the scenario once, and it is the reason the rule exists. Frances came ashore on September 4, 2004 and Jeanne 21 days later, and between them they produced 2,168 of the 3,349 flood claims FEMA holds for Indian River County. Florida treats a second hurricane inside the same calendar year differently from the first, and that arithmetic sits with the rest of the statewide rules on our Florida page.
2024 was a single storm here, not a pair: Milton drew its own declaration for this county in October and that one carried Individual Assistance, while Helene two weeks earlier produced none covering Indian River County at all. Worth knowing, because a second-storm deductible applied to a first-storm loss is a quiet and expensive error in either direction.
Start a Vero Beach Claim Review
No upfront fee. Useful to have in hand: the date it happened, the carrier's estimate and letters, and photographs from before the repairs began.